





One Less Day
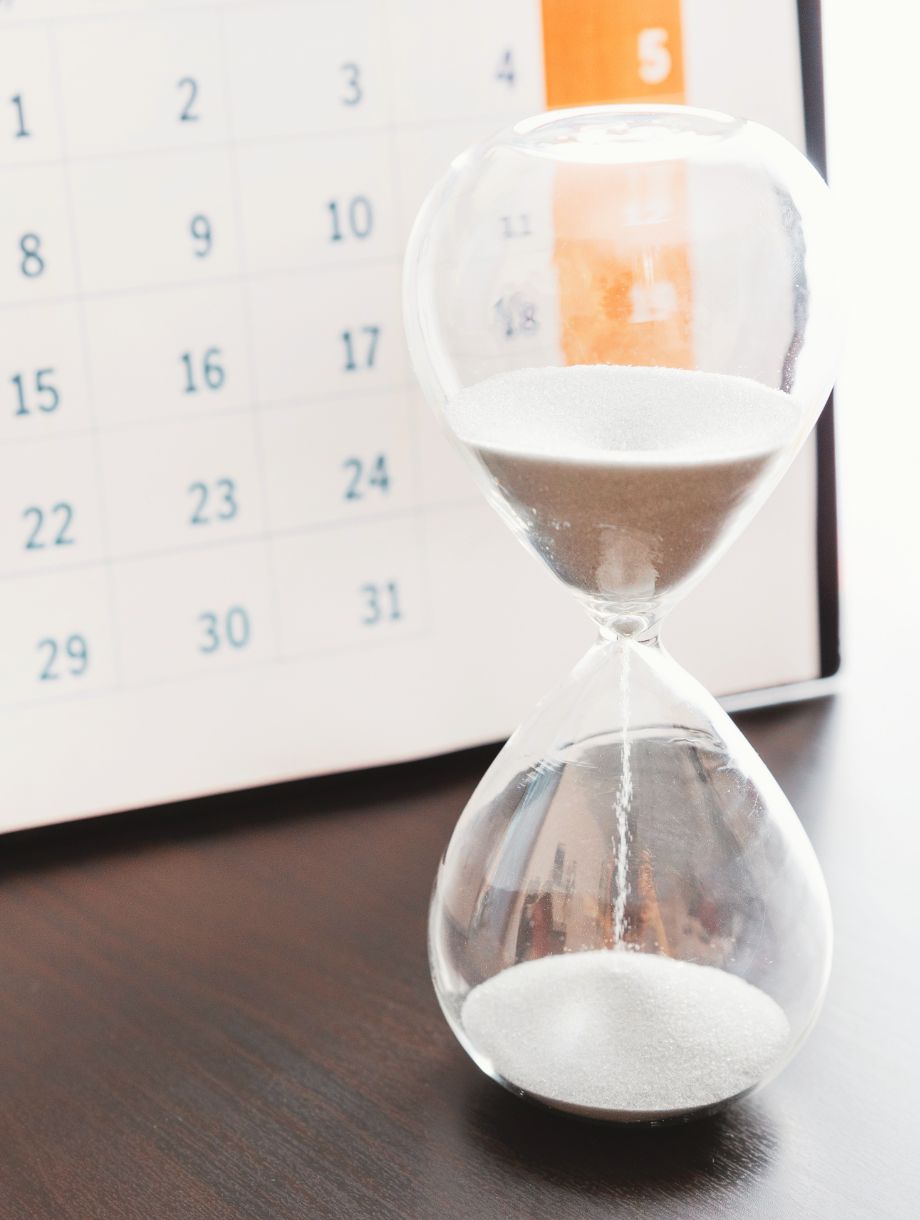
“When we understand that each day isn’t one more day, but one less, we start giving more value to what truly matters.”
That quote has a way of stopping you in your tracks.
It should.
Because most people live as if time is unlimited. They talk about someday. Someday they’ll get serious. Someday they’ll make the call. Someday they’ll build the team. Someday they’ll fix their finances. Someday they’ll protect their family. Someday they’ll start moving with urgency.
But someday is not a strategy.
Every morning we wake up, we are not just receiving another day. We are using one. That truth should not make life feel heavy. It should make life feel valuable.
Every day is a gift. Every day is an opportunity. Every day is a chance to do something that matters before that specific day is gone forever.
You do not get it back.
That is why leadership requires urgency. Not panic. Not pressure. Not noise. Real urgency is quieter than that. It is the focused understanding that what we do matters, people need us, and time is not standing still for anybody.
Financial Education Cannot Wait
The families we are trying to reach are living through that same reality. Their children are getting older. Their debt may be compounding. Their retirement date is getting closer. Their financial decisions are either helping them move forward or quietly pulling them further behind. Their lack of knowledge is either being corrected or exploited.
That is the truth.
People do not need financial education someday. They need it now.
They need to understand how money works before another year passes. They need to know what compound interest is doing for them or against them. They need to know whether they are protected. They need to know whether they are on track. They need to know what their financial future may look like if nothing changes.
And they need someone with the courage to reach out.
That is where WealthWave leaders come in.
We are not just building a business. We are carrying a message. We are leading a mission. We are helping people see what they were never taught, understand what they never learned, and take action before delay becomes regret.
WealthWaveONE Makes Today Count
The beautiful thing is, we have never had better tools to make each day count.
With WealthWaveONE, a leader does not have to wait for the perfect moment, the perfect meeting, the perfect speech, or the perfect event. Today can count.
You can share the Financial Literacy Quiz. You can send TheMoneyBooks. You can share the Golden Apple. You can send a video, a podcast, or a calculator. You can invite someone to an event. You can follow up with someone who already raised their hand. You can help a family take one step closer to financial confidence.
That is what makes this moment so powerful.
WealthWaveONE gives every leader the ability to turn intention into action. It puts the message, the education, the tools, the follow-up, and the opportunity right in your hand.
The question is no longer, “Do I have something to share?”
You do.
The real question is, “Will I share it today?”
Leadership Is Built in Days
Leadership is built in days. Not decades. Not theory. Not good intentions. Days.
One day you make the call. One day you send the message. One day you invite the guest. One day you follow up. One day you help someone understand money differently for the first time in their life. One day you decide your mission deserves more of you.
Then one day becomes a week. A week becomes a month. A month becomes a year. A year becomes a career. A career becomes a legacy.
But it starts with today.
That is why we cannot treat our days casually. A casual day becomes a casual week. A casual week becomes a casual business. A casual business does not change the world.
WealthWave was not built for casual leadership.
It was built for people who understand that financial illiteracy is hurting families every day. It was built for leaders who know education can help prevent exploitation. It was built for men and women who believe people deserve to know how money works, and who are willing to do something about it.
Every day, someone is making a financial decision without the knowledge they need.
Every day, someone is buying the wrong thing.
Every day, someone is carrying the wrong debt.
Every day, someone is under-protected.
Every day, someone is falling further behind.
Every day, someone is wondering if they will ever be able to retire.
And every day, a WealthWave leader can help.
What Will You Do With Today?
That is what makes this work sacred. We do not sell noise. We teach clarity. We do not chase trends. We build understanding. We do not wait for people to magically become financially literate. We bring the education to them.
The tools are ready.
The message is ready.
The mission is ready.
The people are waiting.
So the real question for every leader is simple:
What will you do with today?
Not next week. Not when things slow down. Not when you feel more prepared.
Today.
Use WealthWaveONE. Share the message. Make the contact. Send the link. Invite the family. Follow up with the person who went quiet. Help one more person take the Financial Literacy Quiz. Put TheMoneyBooks in one more hand. Start one more conversation that could change the direction of someone’s life.
That is how you make the day count.
Because one day, all of us will look back. We will not measure our lives only by how many days we had. We will measure them by what we did with the days we were given.
We will remember the people we helped. The families we educated. The leaders we built. The mission we carried. The moments when we chose action over delay. The days when we did not just talk about changing lives, we actually did it.
Each day is not one more.
It is one less.
So do not waste it.
Lead today. Share today. Build today. Teach today. Serve today.
Because today is a gift.
And with WealthWaveONE in your hands, there has never been a better time to make that gift count.

The Torch Is Passing
Knowledge, Liberty, and the WealthWave Mission
For America’s 250th anniversary, the United States Mint has given the nation more than a commemorative half-dollar. It has given us a clear message.
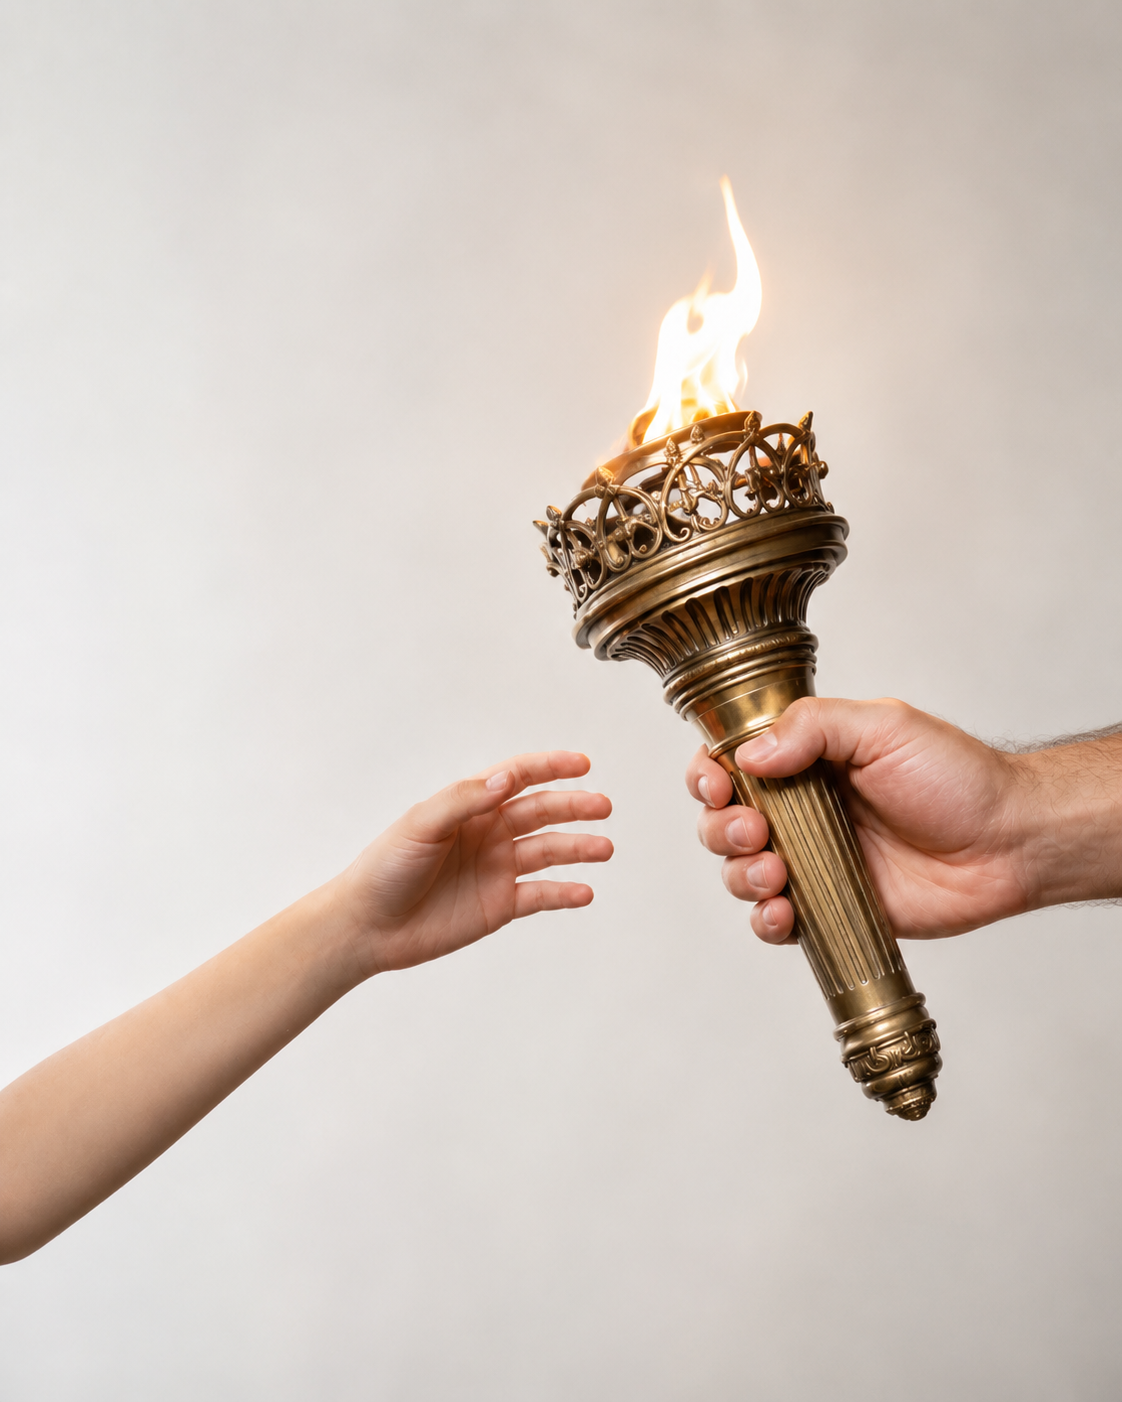
The new Enduring Liberty Half Dollar places the face of the Statue of Liberty on one side, her eyes fixed toward the future. On the other side, Liberty passes her torch to a new generation. Around that torch are words every WealthWave leader should take personally:
“Knowledge is the only guardian of true liberty.”
That is not just a coin inscription. That is a leadership assignment. The U.S. Mint says the 2026 Semiquincentennial coin designs commemorate 250 years of American liberty, and the half-dollar’s reverse shows Liberty passing the torch “with the momentum of purpose” to the next generation.
And that’s exactly what we do. We pass the torch.
Not a theory. Not a slogan. Not a product pitch. We pass knowledge. We teach families what too many were never taught. We help people understand money before money quietly controls their future.
Liberty Without Knowledge Is Fragile
America was built on a radical belief: ordinary people could govern themselves.
That belief changed the world. It gave generations the chance to own property, build businesses, speak freely, worship freely, create opportunity, raise families, and rise by effort, discipline, and vision.
But the Founders understood something many people forget today: liberty does not protect itself.
James Madison warned, “Knowledge will forever govern ignorance,” and said that people who mean to be their own governors must “arm themselves with the power which knowledge gives.”
That sentence should stop every leader in their tracks.
Because ignorance never stays neutral. Ignorance always creates vulnerability.
When people don’t understand money, they may still be free on paper, but they’re exposed in practice. They’re exposed to bad debt, high interest, hidden fees, poor decisions, impulse spending, financial stress, underinsurance, inadequate savings, retirement shortfalls, and advice they don’t know how to evaluate.
A nation can have liberty in law and still have millions of families trapped by financial confusion.
That’s why financial literacy matters.
Money Knowledge Is Freedom Knowledge
Money isn’t everything. But tell that to a family drowning in debt. Tell that to a parent choosing between groceries and a utility bill. Tell that to a worker who spent 40 years on the job and reached retirement with too little saved because no one ever explained compound interest, taxes, inflation, risk, insurance, or the true cost of waiting.
Money may not be the highest thing in life, but it touches almost everything: choices, time, family, health, housing, education, generosity, retirement, dignity, and peace of mind.
That’s why teaching people how money works isn’t a small mission.
It’s not optional work.
It’s liberty work.
The National Financial Educators Council’s 2025 survey estimated that poor financial literacy cost the average American adult $948, adding up to more than $246 billion in estimated nationwide losses. That figure is survey-based, but not knowing how money works can be expensive.
Financial ignorance has a price.
Families pay it in interest.
They pay it in fees.
They pay it in stress.
They pay it in missed opportunity.
They pay it in delayed dreams.
They pay it in futures that could have been stronger.
And here’s the hard truth: most people are not financially illiterate because they are lazy. They’re financially illiterate because no one taught them.
That’s the gap WealthWave was built to close.
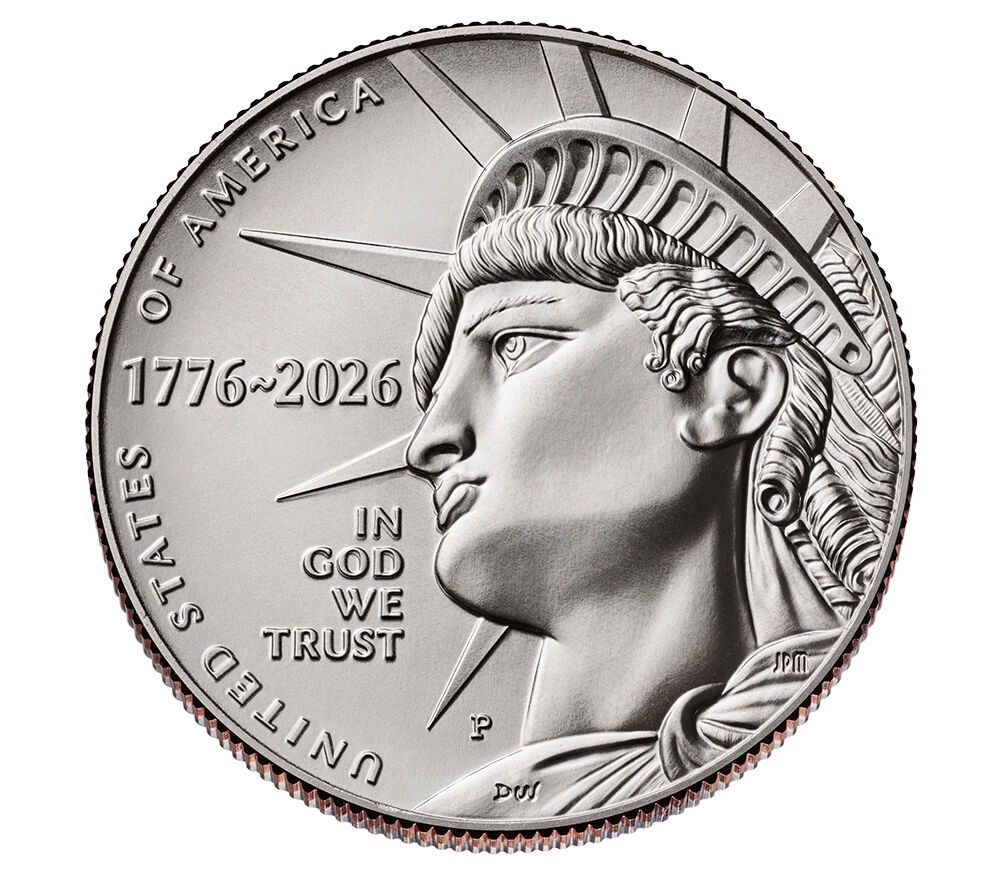
The Coin Carries Our Calling
Think about the symbolism.
A coin is money.
On that coin is Liberty.
And Liberty is holding out a torch.
The inscription says knowledge guards true liberty.
That’s WealthWave in metal.
That’s TheMoneyBooks in one national image.
That’s the WealthWave mission stamped into the American story.
Every time a WealthWave leader sits down with a family and teaches them the Rule of 72, the power of compound interest, the danger of bad debt, the need for protection, the cost of procrastination, or the importance of saving early, that leader is doing more than sharing information.
They’re passing the torch.
Every class matters.
Every appointment matters.
Every book matters.
Every video matters.
Every conversation matters.
Because one clear explanation can change the direction of a family.
And one changed family can influence generations.
Leadership Means Carrying the Torch Before It Is Convenient
The torch does not pass itself.
It has to be carried by people who believe the work matters.
That’s why WealthWave leadership is not just about building an organization. It’s about building people who can build people.
A real leader does not hoard knowledge. A real leader multiplies it.
A real leader does not wait for perfect conditions. A real leader teaches in the middle of confusion.
A real leader does not look at financial ignorance and say, “That’s their problem.” A real leader says, “That’s why I’m here.”
America needs leaders who can explain money clearly, honestly, and courageously. Not in language designed to impress. In language designed to be understood.
Because when people understand, they can act.
And when they act, their future can change.
We Are Fortunate, and We Are Responsible
We should never lose our gratitude for America.
This country isn’t perfect. No country is. But America remains one of history’s greatest engines of opportunity. People still come here because they believe this nation offers a chance to dream, work, build, own, serve, and rise.
That should make us grateful.
It should also make us responsible.
Freedom gives us opportunity, but knowledge helps us use it wisely.
Opportunity without education can be wasted. Income without understanding can disappear. Access without guidance can become exploitation. Goals without a plan can remain dreams.
That’s why our work is so urgent.
We’re not merely building a business. We’re helping families participate more fully in the promise of America.
We’re teaching people how to think, plan, protect, save, invest, and lead their households with confidence.
That’s patriotic work.
That’s generational work.
That’s leadership work.
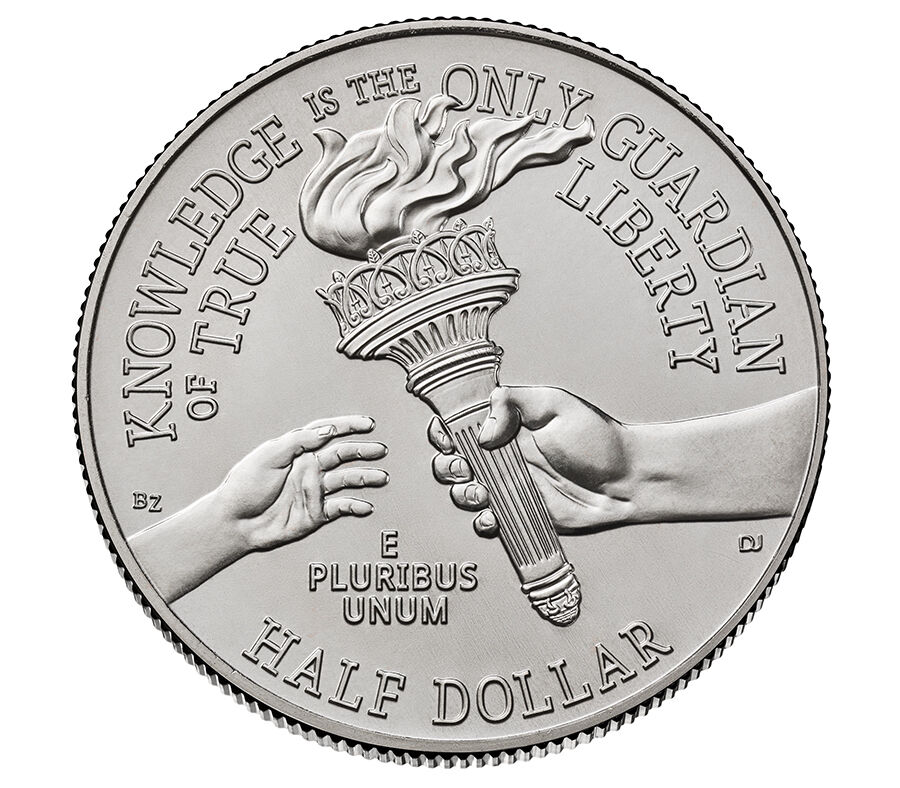
The Message for Every WealthWave Leader
Let this coin remind us who we are.
We’re financial educators.
We’re torchbearers.
We stand between confusion and clarity. Between exploitation and education. Between fear and confidence. Between “I wish someone had taught me” and “now I know what to do.”
The Statue of Liberty does not lower her torch. She lifts it.
That’s our model.
Lift the torch in every community.
Lift the torch in every meeting.
Lift the torch for every family.
Lift the torch for the next generation.
Don’t underestimate the power of one lesson, one book, one conversation, one leader who cares enough to teach.
Knowledge isn’t just information.
Knowledge is protection.
Knowledge is confidence.
Knowledge is opportunity.
Knowledge is dignity.
Knowledge is liberty’s guardian.
And when it comes to money, knowledge can be the difference between being used by the system and understanding how to navigate it.
The Torch Is in Our Hands
America’s 250th anniversary is more than a national celebration. It is a reminder that every generation must decide what it will preserve, what it will improve, and what it will pass on.
Liberty was handed to us at great cost.
Now the torch is in our hands.
For WealthWave leaders, the mission is clear: teach America how money works.
Teach it with urgency.
Teach it with humility.
Teach it with conviction.
Teach it like families are counting on it, because they are.
A coin may carry the words, but leaders must carry the work.
Knowledge is the only guardian of true liberty.
Let’s guard it.
Let’s teach it.
Let’s pass the torch.
Tom Mathews, CFEd®
The Best Time Ever To Be In This Business

Why Leaders Have A Once-In-A-Generation Chance To Teach Families, Build Teams, And Change The Future Of Money
I’ve been doing this business for 45 years.
That’s a long time to do one business, one model, one way. Long enough to see what changes, what doesn’t, what matters, and what never mattered as much as people thought it did.
The products have changed. The technology has changed. The tools have changed. The speed has changed. The way we communicate has changed.
But the mission hasn’t changed.
People still need to understand money.
They still need someone they can trust.
They still need somebody to sit down with them, teach them the basics, help them see what they’ve never been shown, and then help them take action when they’re ready.
That’s why I believe this is the best time ever to be in this business.
Not because it’s easier. It’s not.
Not because people are magically smarter with money. They’re not.
It’s the best time because the need has never been bigger, the tools have never been better, and the world has never been more ready for leaders who can teach first and serve when asked.
The Rules Have Changed
When I got started in the early 1980s, the world looked different.
Back then, a lot of people retired around 60 or 65. Many were gone by 70 or 75. That wasn’t good or bad. That was just the math of life at the time.
Today, it’s not unusual for people to live into their 80s, 90s, and even 100s.
That’s a blessing. I’m all for more time with your family, more years with your children, more years with your grandchildren, more years to enjoy the life you worked so hard to build.
But here’s the truth.
If people are going to live longer, their money has to last longer.
That one change has altered everything.
For generations, people were afraid of dying too soon. Now millions are afraid of living too long and running out of money before they run out of life.
Think about that.
A long life without financial confidence can become a long struggle. A long life with financial education, planning, protection, and action can become one of the greatest gifts a family could ever experience.
That’s why what we do matters so much.
We’re not just talking about products. We’re not just talking about accounts. We’re not just talking about policies, investments, or retirement numbers.
We’re talking about dignity.
We’re talking about families.
We’re talking about parents who don’t want to become a burden to their children.
We’re talking about grandparents who want to say yes more often.
We’re talking about people who worked their whole lives and deserve to understand how money works before it’s too late.
Financial Illiteracy Is The Crisis Nobody Can Ignore
The biggest economic problem in the world isn’t that people are lazy.
It isn’t that people don’t care.
It isn’t that people don’t work hard enough.
Most people work very hard. They show up. They raise families. They pay bills. They try to do the right thing.
The problem is that most people were never taught how money works.
They didn’t learn it in school. They didn’t learn it at work. Many didn’t learn it from their parents because their parents were never taught either.
So where are they supposed to learn it?
Too often, they end up trying to learn from the same financial industry that benefits from what they don’t know.
That’s the danger.
When someone doesn’t understand money, they can become a victim of someone who does. They can be sold things they don’t understand. They can make decisions they didn’t know were dangerous. They can lose years, sometimes decades, because nobody ever took the time to explain the basics in plain language.
That’s why WealthWave exists.
We teach.
We educate.
We help people see what they’ve never been shown.
And when you teach somebody the basics of money, something amazing happens. They usually look back at you and say, “Can you take a look at mine?”
That’s the business.
You don’t have to be a slick salesperson. You don’t have to pressure anybody. You don’t have to act like somebody you’re not.
You can be a teacher.
You can be an educator.
You can be the person who helps a family finally understand what they need to do next.
Teach First. Serve When Asked.
If there’s one principle I wish every WealthWave leader would burn into their heart, it’s this:
Teach first. Serve when asked.
That’s not a slogan. That’s a way of doing business.
It’s also one of the reasons I’ve been able to stay in this business for 45 years with peace of mind.
When I was 22 years old and single, I had one basic rule for myself. Before I recommended anything to anybody, I asked myself a simple question:
Would I do this for my mom?
That was it.
My mom was the person I loved most in the world. So if the answer was yes, I could consider doing it. If the answer was no, I couldn’t do it and I wouldn’t do it.
That rule has served me my whole career.
Put the consumer first.
Actually, put the consumer only.
Don’t put yourself first. Don’t put your company first. Don’t put the product provider first. Put the consumer first.
When a family puts their trust in your hands, that’s sacred. They’re not just handing you numbers. They’re handing you their dreams, their fears, their children’s future, their retirement, their protection, their hope.
Treat it that way.
If you do, you can build a great business. More importantly, you can build one that lasts.
The Rule Of 72 Still Opens Eyes
Some leaders get bored with the basics because they’ve seen them so many times.
That’s a mistake.
The prospect hasn’t seen them.
The new associate hasn’t seen them.
The family sitting across from you may have worked for 20 or 30 years and never once had anybody show them how money doubles, how debt grows, how time works, or why waiting can cost them so much.
The Rule of 72 is not old.
It’s not outdated.
It’s not a beginner lesson you rush through.
It’s one of the most powerful doorways into financial literacy.
I remember being in a room with million-dollar earners, and the question was asked, “When did you know this could become your life’s work?”
Every single one of them said some version of the same thing:
“When I saw the Rule of 72.”
That’s how powerful the basics can be when they’re said right.
When people see that their money in a low-rate account may take forever to double, while credit card debt can double in just a few years, it rocks them.
It wakes them up.
It makes them realize money is either working for them or against them.
That’s when education becomes personal.
That’s when they start thinking about their own life, their own debt, their own savings, their own insurance, their own investments, their own children, their own future.
That’s when they stop hearing a presentation and start seeing themselves in the story.
Education Without Action Is Meaningless
Teaching is powerful, but teaching alone isn’t enough.
Education without action is meaningless.
If somebody learns how money works and then keeps doing everything the same old way, what was the point?
Our job isn’t to impress people with information. Our job is to help people understand enough to move.
Move toward protection.
Move toward saving.
Move toward investing.
Move toward eliminating bad debt.
Move toward building income.
Move toward getting licensed.
Move toward becoming an entrepreneur.
Move toward a better life.
That’s why the WealthWave mission is so powerful. We don’t just teach people what’s wrong. We help them see what’s possible.
And for some people, the most important financial concept we can introduce them to isn’t just compound interest. It’s entrepreneurship.
Because sometimes a family doesn’t just need a better product.
Sometimes they need more income.
Sometimes they need a business.
Sometimes they need a way to build something they own, something they can grow, something that gives them a chance to become a different version of themselves.
Don’t ever forget that.
When you introduce somebody to this business, you may be giving them more than an opportunity. You may be giving them a new identity.
Somebody introduced you to this business.
Aren’t you glad they didn’t just try to make you a client?
This Business Is About Difference, Not Just Dollars
People can make great money here.
That’s true, and I’m not going to apologize for it.
Free enterprise is a beautiful thing. If you work hard, build a team, serve people well, and stay in the game, you should be able to win financially.
But this business can never become only about the money we make.
It has to stay about the difference we make.
If I were holding a convention today, I could spend the whole time talking about that.
The money will follow the mission if the mission stays pure.
The income will follow the impact if the impact is real.
The recognition will follow the work if the work is consistent.
The danger is when leaders start talking more about what they can earn than who they can help.
That’s backward.
Talk about the family that can retire with confidence.
Talk about the parent who can send a child to college.
Talk about the widow who won’t be financially lost.
Talk about the young person who starts investing early because somebody finally showed them the math.
Talk about the new associate who gets licensed, finds their voice, builds belief, and becomes a leader.
That’s what this is really about.
The money matters, but the mission matters more.
Build The Team, Because The Team Compounds
The compounding of a team works a lot like the compounding of money.
In the beginning, it can look like nothing is happening.
You invite people. You follow up. You teach. You train. You run meetings. You help people get licensed. You repeat yourself. You wonder if anybody is listening. You wonder if it’s working.
Then one day, it starts to move.
A teammate gets serious.
A new leader emerges.
Somebody gets licensed.
Somebody brings a guest.
Somebody earns a ring.
Somebody you believed in starts believing in themselves.
And then it compounds.
That’s why I’ve always taught people to build a big team. Not just write business. Build a business.
Writing business is good.
Building a team is better.
Helping other people write business, build teams, and become leaders is where the real scale happens.
That’s where overrides come from.
That’s where long-term business comes from.
That’s where the fun comes from.
That’s where leadership becomes more than your personal production. It becomes a movement of people who can carry the mission farther than you ever could by yourself.
If you think small, you’ll build small.
If you work small, you’ll stay small.
But if you think big, learn the words, do the work, and build people, this business can become bigger than you imagined.
This Is A Business Of Words
I believe this is a business of words.
If you have the words, you can do this.
Most people don’t struggle because they don’t care. They struggle because they don’t know what to say.
They don’t know how to invite.
They don’t know how to explain.
They don’t know how to follow up.
They don’t know how to teach the Rule of 72 so it lands.
They don’t know how to introduce the business without sounding pushy.
They don’t know how to talk about money without making people defensive.
Words matter.
There are words that are magic.
There are words that are good.
There are words that are just okay.
And there are words that don’t work.
A leader’s job is to learn the words that open minds, build trust, and help people take the next right step.
That’s not manipulation. That’s leadership.
When your heart is right and your words are right, people can feel it.
They don’t feel sold.
They feel served.
Technology Is Giving Us A Bigger Voice
When I got started, everything was slower.
Paper. Print. Checks. In-person meetings. Phone calls. Mail. Everything took longer.
I had one of the first laptop computers in our business. Back then, a lot of people thought computers were optional.
They weren’t.
Today, everybody has computers everywhere. In their homes, cars, phones, watches, offices, and pockets. We don’t even think about it anymore.
Now history is repeating itself with AI.
Some people are scared of it. I understand that. But I don’t see AI replacing what we do. I see it increasing what the right leader can do.
A financial professional using AI can be more powerful than AI by itself or a financial professional by themselves.
The same is true with all of today’s tools. Texting, emailing, video, podcasts, websites, books, streaming events, social media, apps, presentations, and follow-up systems.
These tools don’t replace leadership.
They multiply leadership.
They don’t replace trust.
They help us reach more people with trust.
They don’t replace the human being sitting across the table.
They help that human being show up better prepared, better informed, and better equipped.
But remember this: the tool is never the mission.
The mission is financial literacy.
The mission is leadership.
The mission is families.
The mission is helping people take action.
Women Will Help Lead The Future Of This Industry
One of the biggest changes I’ve seen is the rise of women in this business.
When I got started, the industry was overwhelmingly men. That’s changing, and it needs to change.
Women are already leading families financially in ways many people don’t fully recognize. They manage households. They make decisions. They care deeply about security, children, aging parents, protection, and the future.
And when women learn how money works, they act.
They don’t just sit around and admire the idea. They put it in place.
That’s why I believe women are going to do to the financial industry what they did to residential real estate. They’re going to become a much bigger force, and the leaders who understand that now will be ahead of the curve.
Women don’t need to be talked down to.
They don’t need mansplaining.
They need respect, clarity, education, and opportunity.
They need other women leaders who can sit across from them and say, “I get it. I understand what you’re carrying. Let me show you how this works.”
Men should be excited about that, not threatened by it.
If you’re a WealthWave leader, build more women into your business.
Not because it sounds nice.
Because it’s right.
Because it’s needed.
Because it’s smart.
Because the future is already moving that way.
The Next 25 Years Can Be Bigger Than The Last 45
I’ve had the blessing of being around this business a long time.
I learned from originals.
I watched the early days.
I saw the struggles, the breakthroughs, the systems, the campaigns, the books, the leaders, the growth, and the evolution.
I’ve also seen enough to say this with confidence:
We’ve never been better at saying what we say.
We’ve never been better at doing what we do.
We’ve never had better tools.
We’ve never had a bigger need.
We’ve never had a clearer mission.
That should excite every WealthWave leader.
But it should also challenge you.
Don’t waste this moment.
Don’t shrink your dream down to what yesterday’s version of you could handle.
Don’t make this business smaller than it is.
Don’t make it only about sales.
Don’t make it only about income.
Don’t make it only about your next promotion.
Those things matter, but they’re not the whole mission.
Make it about the family that finally understands.
Make it about the leader who finally believes.
Make it about the woman who finally sees herself in this business.
Make it about the young person who learns early enough to change their future.
Make it about the retiree who doesn’t have to live scared.
Make it about the new associate who looks in the mirror one day and realizes they’ve become someone they never thought they could become.
That’s leadership.
That’s WealthWave.
That’s why we do this.
We’re Here To Teach, Build, And Change The World
I’m not here to sell books.
I’m not here to sell products.
I’m not here to sell hype.
I’m here to make the world financially literate.
I’m here to help families become smart with money.
I’m here to help entrepreneurs learn how to build a business, not just sell a product.
I’m here to help leaders find the words, build the team, and carry this mission into the future.
And if you’re a WealthWave leader, that’s your opportunity, too.
Teach first.
Serve when asked.
Put the consumer only.
Build the team.
Learn the words.
Use the tools.
Develop the women.
Think bigger.
Work harder.
Stay positive.
And never forget what business you’re really in.
We’re in the business of helping people see what they’ve never seen, learn what they were never taught, and become what they may never have believed was possible.
That’s why this is the best time ever to be in this business.
And if we do this right, the next 25 years won’t just be bigger.
They’ll matter even more.
Tom Mathews, CFEd®
The Magic Number Just Got Bigger
Why Knowing Your Numbers May Be The First Step Toward Financial Confidence
Retirement planners have talked for years about the “magic number,” the amount of money Americans believe they’ll need to retire comfortably.
That number just got bigger.
According to Northwestern Mutual’s 2026 Planning & Progress Study, Americans now believe they’ll need $1.46 million to retire comfortably. That’s up $200,000 from last year and back in line with the 2024 estimate. The study also found that 46% of Americans don’t expect to be financially prepared for retirement, and 48% believe it’s somewhat or very likely they could outlive their savings.
That should stop every WealthWave leader in their tracks.
Not because $1.46 million is the perfect number for everyone. It isn’t.
Not because every family needs the same retirement goal. They don’t.
But because this number tells a bigger story. Americans are feeling the pressure of inflation, longer lives, rising healthcare costs, uncertainty around Social Security, and the reality that retirement could last 20, 30, or even 40 years.
The math is getting louder.
And most people still don’t know how to listen to it.
The Math Doesn’t Change Because You Don’t Know It
Money has rules.
Compound interest has rules. Inflation has rules. Debt has rules. Taxes have rules. Longevity has rules. Retirement income has rules.
Those rules don’t change because someone never learned them. They don’t change because someone is busy, overwhelmed, embarrassed, or afraid to look. They don’t change because schools didn’t teach them or because the financial world made everything sound more complicated than it needed to be.
The math is the math.
It doesn’t care whether someone understands it. It doesn’t wait until they’re ready. It doesn’t pause because life got hard. It keeps moving.
That’s why financial education matters so much.
A person can’t fix what they haven’t measured. They can’t aim at a future they haven’t defined. They can’t close a gap they don’t know exists. They can’t make confident decisions if they’re guessing.
This is where WealthWave comes in.
We don’t show up to scare people. We show up to educate them. We help people turn fear into facts, confusion into clarity, and numbers into a plan.
A Magic Number Isn’t Magic At All
The phrase “magic number” sounds nice, but there’s nothing magical about retirement planning.
A retirement number is really just the answer to a series of questions:
How long might you live?
When do you want to stop working full-time?
What lifestyle do you want?
How much income will you need every month?
What role will Social Security play?
What savings do you already have?
How much are you saving now?
What rate of return are you assuming?
What happens if inflation runs higher?
What happens if healthcare costs rise?
What happens if you live longer than expected?
Those questions don’t have to be frightening. They just have to be answered.
That’s why the WealthWaveONE Sharing app is such a powerful tool. The Investment Goal Calculator helps turn the conversation from vague hope into visible math. In just a few moments, a person can begin to see where they are, where they want to go, and what it may take to get there.
That’s not pressure. That’s education.
And education is the beginning of control.
Most People Don’t Need More Opinions. They Need Their Numbers.
One of the biggest problems in America is that too many people are trying to build their financial future with opinions instead of numbers.
They think they’re doing okay.
They hope they’re saving enough.
They assume Social Security will cover more than it may.
They believe they’ll work longer, even though health, layoffs, caregiving, or life itself may have other plans.
They guess.
But guessing is not a strategy.
Fidelity’s retirement guideline suggests aiming to save 10 times your income by age 67, with milestone goals along the way, including 1x income by age 30, 3x by 40, 6x by 50, and 8x by 60. Northwestern Mutual also points to rules of thumb like the 25x Rule, the $1,000-a-Month Rule, and the 4% Rule as ways to start thinking about retirement income. A $1.46 million nest egg, using a 4% first-year withdrawal concept, would represent about $58,000 a year, or roughly $4,800 a month before considering taxes, inflation, market changes, and personal circumstances.
That’s the kind of conversation people need.
Not theory.
Not noise.
Not financial jargon.
Just clear, simple, honest math.
This Is A WealthWave Moment
WealthWave leaders need to understand what this moment really means.
When a national headline says Americans may need $1.46 million to retire comfortably, millions of people don’t know what to do with that information. Some will ignore it. Some will panic. Some will assume it’s impossible. Some will say, “I’ll never get there,” and give up before they even begin.
That’s why we can’t just read headlines. We have to turn headlines into conversations.
Every WealthWave leader should be using this story as a reason to reach out, educate, and serve.
Share the USAToday article. Share the thought. Open the WealthWaveONE Sharing app. Use the Investment Goal Calculator. Help someone see their own number.
Then invite them to take the Financial Literacy Quiz at TakeTheFLQ.com.
The FLQ is like a financial GPS. Before a GPS can help you get where you want to go, it has to know where you are. The same is true with money. People need to know where they stand before they can build a better path forward.
The Investment Goal Calculator helps them see the target.
The FLQ helps them see their starting point.
Together, they create one of the most important conversations we can have with a family.
People Don’t Need Shame. They Need A Map.
Let’s be clear. A lot of people are behind.
That doesn’t make them bad. It makes them normal.
The typical American family is dealing with rising costs, debt, taxes, kids, aging parents, medical bills, college costs, housing, and the daily pressure of just keeping life moving. Many people were never taught the basics of money. They were handed credit cards before they understood interest. They were told to save for retirement before they understood compounding. They were asked to choose benefits, investments, insurance, and loans without a real education in how any of it works.
That’s not a personal failure.
That’s an education failure.
And WealthWave exists to help fix it.
Our job is not to make people feel small because they don’t know. Our job is to help them feel powerful because now they can know.
Once people know their numbers, everything changes.
They can see the gap.
They can understand the time frame.
They can adjust the savings rate.
They can protect the income.
They can reduce bad debt.
They can learn how compounding works.
They can make decisions with confidence instead of fear.
No one can go back and start earlier. But almost everyone can start now.
The Calculator Creates The Conversation
The Investment Goal Calculator is not just a tool.
It’s a doorway.
It gives WealthWave leaders a simple way to move from small talk to real talk. It helps people see that retirement planning isn’t some mysterious financial mountain. It’s a math problem. A big one, maybe. An emotional one, often. But still a math problem.
And math problems can be worked.
When you sit with someone and show them how time, money, interest, and consistency work together, you’re doing more than explaining retirement.
You’re giving them language they may never have had before.
You’re helping them understand the cost of waiting.
You’re helping them see the power of starting.
You’re helping them discover that a better future may not require perfection. It requires awareness, discipline, time, and a plan.
That’s leadership.
Outliving Money Is A Real Fear
One of the deepest financial fears in America is not simply retirement.
It’s outliving your money.
People aren’t just worried about stopping work. They’re worried about losing independence. They’re worried about becoming a burden. They’re worried about healthcare costs, inflation, long-term care, and whether the income they spent decades building will last as long as they do.
Longer life is a blessing, but it also comes with responsibility. If people may live 20, 30, or 40 years in retirement, then financial literacy can’t be optional. It has to become part of how families prepare for life.
That’s why our work matters.
We’re not just talking about money.
We’re talking about dignity.
We’re talking about choices.
We’re talking about families.
We’re talking about the difference between hoping life works out and knowing what steps to take next.
The Leader Who Shares The Most Can Help The Most
WealthWave is a contacting business.
That means every leader has to decide whether they’re going to watch the news or use the news.
This headline gives us a reason to talk to people.
Not with hype. Not with fear. Not with pressure.
With care.
Here’s a simple way to say it:
“I saw something important today. The latest study says Americans now believe they’ll need $1.46 million to retire comfortably. I don’t know what your number is, and honestly, most people don’t. But we have a simple calculator that can help you get a clearer idea. It only takes a few minutes. You should also take the Financial Literacy Quiz at TakeTheFLQ.com. It’ll help you see where you stand.”
That’s simple.
That’s honest.
That’s valuable.
And that’s duplicatable.
Every WealthWave leader can do that.
Know Your Number. Know Your Future.
The biggest financial danger in America may not be a lack of money.
It may be a lack of clarity.
People don’t know what they need. They don’t know what they have. They don’t know what they’re on track for. They don’t know what inflation can do. They don’t know how compound interest works. They don’t know how long retirement may last. They don’t know what questions to ask.
But they can learn.
And when they learn, they can act.
That’s the mission.
That’s the opportunity.
That’s why WealthWave leaders have to be bold enough to bring this conversation to the people they care about.
The “magic number” just got bigger, but the answer isn’t magic.
It’s education.
It’s awareness.
It’s action.
It’s knowing your numbers and knowing what they mean.
Because once people understand the math, they can stop guessing and start building.
And when a family finally sees the path clearly, they don’t just gain information. They gain hope.
Finding True North
Why The FLQ May Be The Most Important First Step In A Person’s Financial Life
If you’re physically lost, the first thing you need is not motivation.
You need direction.
You need a map. You need a compass. You need a clear understanding of where you are, where you’re trying to go, and what path can get you there.
Money works the same way.
If someone is financially lost, guessing harder won’t fix it. Hoping won’t fix it. Ignoring the problem won’t fix it. And scrolling through random opinions online won’t fix it.
The first step is measurement.
That’s why the Financial Literacy Quiz, the FLQ at TakeTheFLQ.com, matters so much.
The FLQ is not just a quiz. It’s a financial compass. It helps people discover what they know, what they don’t know, and where they need to grow. It gives them a starting point. It gives them language. It gives them clarity.
And clarity is where confidence begins.
The FLQ helps people answer one of the most important questions in their financial life:
“Am I financially literate enough to make informed decisions about my future?”
For millions of Americans, the honest answer is no.
And that’s not an insult. It’s the truth. Most people were never taught how money works. They were told to get good grades, get a good job, work hard, pay their bills, and hope it all works out.
Hope is not a financial strategy.
Financial literacy is.
America Is Financially Lost
The data is not complicated. It’s disturbing.
The 2025 TIAA Institute-GFLEC Personal Finance Index found that U.S. adults answered only 49% of personal finance questions correctly on average. That’s not a passing grade. That’s a national warning light. The same study found that risk comprehension remains the weakest area, with only 36% of risk-related questions answered correctly. It also found that adults with very low financial literacy are twice as likely to be debt-constrained and three times more likely to be financially fragile. (TIAA)
FINRA Foundation’s 2025 state-by-state financial knowledge findings were just as sobering. Only 27% of respondents correctly answered at least five of seven basic financial knowledge questions. (FINRA)
The cost is real. The National Financial Educators Council reported that financial illiteracy cost Americans more than $246 billion in 2025, with the average adult estimating a loss of $948 because of a lack of financial knowledge. (NFEC)
That’s not just a statistic.
That’s a family paying too much interest.
That’s a parent without enough life insurance.
That’s a worker delaying retirement.
That’s a widow confused by accounts she never understood.
That’s a young adult learning about debt the hard way.
That’s a retiree afraid of running out of money.
Financial illiteracy doesn’t just cost dollars. It costs confidence, opportunity, security, and dignity.
The FLQ Turns Confusion Into A Starting Point
When people are lost, they often feel embarrassed.
They don’t want to admit they don’t understand compound interest, inflation, taxes, insurance, investing, retirement income, long-term care, or risk.
So they pretend. They delay. They avoid. They guess.
That’s how bad decisions become expensive decisions.
The FLQ changes the conversation. It makes financial literacy measurable, approachable, and personal. According to TakeTheFLQ.com, the Financial Literacy Index is designed to provide ongoing insights into financial literacy across demographics, identify knowledge gaps, and help communities improve financial well-being. The FLQ helps people discover where they stand, learn how to improve, and contribute to broader research. (Financial Literacy Index)
That’s powerful.
Because once someone sees their score, they don’t have to stay stuck.
They can take the next step.
The FLQ gives WealthWave leaders a simple, honest, non-threatening way to start a conversation:
“Let’s find out where you are, then we can help you move forward.”
That’s leadership.
That’s education first.
That’s how you serve when asked.
Information Is Everywhere. Wisdom Is Not.
We live in the most connected financial information age in history.
People can search anything. Watch anything. Ask AI anything. Follow anyone.
But access to information is not the same as financial literacy.
A person can watch videos about investing and still not understand risk.
They can read posts about retirement and still not know how much they need.
They can hear opinions about life insurance and still be dangerously under-protected.
They can ask AI a question and still not know whether the answer applies to their situation.
That’s why the human relationship still matters.
Gallup found that when seeking financial advice, U.S. adults are most likely to turn to friends and family at 43%, followed closely by financial advisers and planners at 41%. But that also means millions of people are still relying first on people who may love them, but may not be qualified to guide them. (Gallup.com)
Investopedia, citing Gallup and other research, reported that only 41% of Americans use financial advisors, and younger adults rely on professionals even less. Among 18- to 29-year-olds, only 27% use financial advisors, while 42% turn to social media. (Investopedia)
That is the problem.
People are making some of the most important financial decisions of their lives with incomplete knowledge, unverified sources, and no real plan.
That’s not freedom.
That’s financial wandering.
Why A Licensed Financial Professional Matters
The FLQ helps people locate where they are.
A trusted, licensed financial professional helps them decide what to do next.
That matters because financial decisions are not just academic. They are personal. They involve tradeoffs. They involve risk. They involve family. They involve timing. They involve products, laws, taxes, goals, emotions, and consequences.
The U.S. Bureau of Labor Statistics explains that personal financial advisors help individuals manage money and plan for their financial future, including guidance around investments, insurance, mortgages, estate planning, taxes, retirement, education expenses, and short- and long-term goals. (Bureau of Labor Statistics)
A good licensed financial professional can help people:
1. Understand Their Current Financial Reality
Most people don’t have a financial plan because they don’t know where to begin.
A professional can help organize the moving parts: income, debt, savings, protection, retirement accounts, insurance, goals, risks, and time horizons.
The FLQ reveals the knowledge gaps. The professional helps connect those gaps to real-life decisions.
2. Turn Education Into Action
Knowing more is important.
Doing better is the goal.
A person may learn that debt is dangerous, but still need help building a debt-reduction strategy. They may understand compound interest, but still need help starting early enough. They may realize they’re underinsured, but still need help choosing the right coverage. They may know retirement matters, but still need help calculating what it will take.
Education creates awareness.
Action creates progress.
3. Avoid Costly Mistakes
Financial mistakes are often expensive because they compound.
A bad loan, a missed match, an uncovered risk, an emotional investment decision, an early withdrawal, a poorly structured retirement strategy, or the wrong insurance decision can cost a family for years.
The right professional can help people slow down, ask better questions, compare options, and make informed decisions.
4. Protect Against Fraud And Unqualified Advice
This is critical.
The SEC’s Investor.gov warns that unlicensed, unregistered persons commit much of the investment fraud in the United States. It urges consumers to check whether a financial professional is licensed and registered through tools like IAPD and FINRA BrokerCheck, where they can also review disciplinary history. (Investor.gov)
That one point should be shouted from the rooftops:
Before you take financial advice, verify who is giving it.
Trust should be earned.
Licensing matters. Registration matters. Background matters. Disclosure matters.
5. Build Confidence Through A Real Plan
CFP Board’s Financial Planning Longitudinal Study found that Americans working with CFP® professionals reported stronger outcomes and greater well-being than people working with other advisors or those who were unadvised. The study found that 78% of CFP® professional-advised clients maintained three-month emergency funds, compared with 53% of non-advised individuals. It also found higher rates of wills, detailed retirement plans, comprehensive investment strategies, and reduced financial anxiety. (CFP Board)
Northwestern Mutual’s 2026 Planning & Progress Study found that among Americans with a financial advisor, 71% said they felt financially secure, while only 10% said they did not. (Newsroom | Northwestern Mutual)
That’s not because a professional magically fixes everything.
It’s because a plan changes how people see the future.
When people understand what they’re doing and why they’re doing it, they stop wandering.
They start walking.
The WealthWave Leader’s Role
This is where WealthWave leaders must see the moment clearly.
We’re not here to impress people with how much we know.
We’re here to help people discover what they need to know.
That’s different.
The FLQ is not a sales tool. It’s a service tool. It opens the door to education. It helps people lower their guard. It gives families a way to talk about money without shame. It gives leaders a way to start with value instead of pressure.
The conversation can be simple:
“If you were lost on the road, you’d use GPS. If you’re unsure about money, you need a financial compass. Take the FLQ. Let’s see where you are. Then we can help you understand the next right step.”
That’s not complicated.
That’s powerful.
Because people don’t need another financial lecture.
They need someone to help them find True North.
True North Is Not A Product
True North is not a policy.
True North is not an account.
True North is not a rate of return.
True North is financial clarity.
It’s knowing how money works.
It’s knowing what risks you face.
It’s knowing what decisions matter most.
It’s knowing what questions to ask.
It’s knowing who to trust.
It’s knowing the difference between information and advice.
It’s knowing that your future deserves more than guessing.
For WealthWave, the mission has never been more relevant.
America doesn’t just need more financial products.
America needs more financial education.
America needs more leaders who can teach first, serve when asked, and help people make informed decisions with confidence.
The FLQ gives us a way to begin that mission with almost anyone.
A young adult.
A couple.
A parent.
A business owner.
A teacher.
A nurse.
A police officer.
A retiree.
A widow.
A family trying to get out of debt.
A professional trying to prepare for retirement.
A leader wondering whether WealthWave could become their mission too.
Everyone has a financial starting point.
The FLQ helps them find it.
The Call To Leadership
Here’s the challenge for every WealthWave leader:
Don’t just talk about financial literacy.
Measure it.
Don’t just tell people they need help.
Show them where they stand.
Don’t just offer information.
Guide them toward action.
Invite people to take the FLQ. Encourage couples to take it together. Encourage parents to talk about the results with their children. Encourage business owners to share it with employees. Encourage leaders to use it in communities, classrooms, churches, companies, and conversations.
Because every FLQ completed is more than a quiz score.
It’s a person taking the first step out of confusion.
It’s a family beginning a better conversation.
It’s a community becoming more aware.
It’s a leader choosing to serve.
And it may be the first time someone has ever stopped long enough to ask:
“Do I really know how money works?”
That question can change a life.
The Compass And The Guide
A compass doesn’t move your feet.
It shows you the direction.
The FLQ can show people where they are.
Financial education can show them what they need to learn.
A trusted, licensed financial professional can help them turn knowledge into decisions.
But the person still has to take the step.
That’s why our work matters.
We are not just building businesses. We are building direction. We are helping people move from confusion to clarity, from fear to confidence, from financial wandering to financial True North.
Financial literacy is not a luxury.
It’s a necessity.
And for millions of Americans, the journey can begin with one simple question:
“Are you willing to find out where you really stand?”
Because once people know where they are, they can finally start moving toward where they were meant to go.
Take the FLQ. Find your True North. Then take action.
Memorial Day Reminds Us Freedom Has a Price
The Cost of Summer Is Exposing America’s Financial Strain
Memorial Day is not just the unofficial start of summer.
It’s not just backyard cookouts, crowded airports, beach traffic, lake weekends, sale signs, packed highways, and the first big family trip of the season.
Memorial Day is a sacred reminder that freedom has never been free.
Before we talk about vacations, gas prices, airline tickets, hotel bills, credit cards, and the financial pressure families are carrying into summer, we should pause long enough to remember the men and women who gave their lives so the rest of us could live ours.
They paid the highest price.
They gave up every future summer, every family gathering, every road trip, every sunset, every ordinary moment most of us take for granted. Their sacrifice gave America the freedom to build, travel, work, worship, dream, speak, gather, and live with possibility.
That’s why Memorial Day should do more than start a season.
It should wake us up.
Because freedom is not only something a nation defends. It’s also something a family has to build.
And for millions of American families, financial freedom feels farther away than it should.
Every year, Memorial Day weekend arrives wrapped in the same American promise: open roads, sunshine, family memories, beach trips, ball games, reunions, and a few days to breathe. Airports overflow. Highways clog. Hotels fill. Families tell themselves that no matter how expensive life gets, summer is still worth it.
And in many ways, it is.
Time matters. Memories matter. Children remember moments. Families need joy. People need rest. Life can’t become nothing but bills, work, stress, and survival.
But this year, the math is harder to ignore.
Families are entering the summer travel season already stretched. Gas is expensive. Airfare is expensive. Hotels are expensive. Restaurants are expensive. Groceries are expensive. Everyday life costs more than many households were prepared for.
Inflation may not dominate the headlines like it once did, but families know the truth because they live it every day. The grocery cart tells the truth. The credit card statement tells the truth. The gas pump tells the truth. The checking account tells the truth.
A family filling up a large SUV for a road trip can feel like they’re paying a utility bill. A family of four flying anywhere can feel like they’re making a major financial decision, not planning a vacation. Even the old idea of “let’s save money and just drive” doesn’t feel as simple anymore.
The American summer vacation is becoming a financial stress test.
And here’s the part nobody likes to say out loud.
Many families aren’t traveling because they can comfortably afford it. They’re traveling because they feel like they have to.
They don’t want to disappoint their kids. They don’t want to break a tradition. They don’t want another summer to pass without doing something meaningful. They don’t want to look back and feel like they missed life while trying to keep up with it.
That’s understandable.
But it’s also dangerous.
Because the emotional economy is overpowering the financial one.
More Americans are using credit cards, payment plans, and “we’ll deal with it later” thinking to fund experiences they can’t really afford. They’re not just paying more for travel. Many are borrowing more to protect the feeling of normal.
That’s where financial pressure becomes financial pain.
A vacation that creates memories should not create months of anxiety. A long weekend should not become a long-term balance. A trip meant to bring a family closer should not quietly push that family deeper into debt.
That’s not freedom.
That’s a trap with better scenery.
Social media has made it worse. Vacations are no longer just about rest. Too often, they’ve become proof. Proof that we’re doing well. Proof that our family is happy. Proof that we’re keeping up. Proof that life is still exciting.
But a picture can hide a payment plan.
A beach photo can hide a credit card balance.
A perfect post can hide a very real financial problem.
This is why financial literacy matters so much.
People don’t get exploited only because someone tricks them. They also get exploited because they were never taught how money really works. They were taught how to earn it, spend it, borrow it, and worry about it. But too many were never taught how to protect it, grow it, manage it, and make confident decisions with it.
That has to change.
Financial literacy is not about telling people to stop living. It’s about helping people live better.
It’s not about canceling every trip, saying no to every memory, or turning life into a spreadsheet. It’s about understanding the real cost of the choices we make before the bills show up later.
A financially literate family can still travel.
They just plan differently.
They know the number before they go. They set a budget and respect it. They compare options. They avoid high-interest debt. They understand opportunity cost. They build memories without pretending money doesn’t matter.
That’s not being cheap.
That’s being wise.
There’s a big difference between making memories and mortgaging peace of mind.
Memorial Day should remind us of what freedom really means. Freedom is the ability to choose with clarity, not panic. Freedom is being able to enjoy a family trip without fearing the statement that arrives after it. Freedom is having the education, discipline, and confidence to say, “This is what we can do, this is what we can’t do, and we’re still going to make this summer meaningful.”
Some families may need to scale back.
That’s not failure.
Some may need to take a shorter trip, stay closer to home, cook more meals, drive instead of fly, visit relatives, use points, split costs, or create meaningful experiences that don’t require financial strain.
That’s not losing.
That’s leadership.
The goal is not to impress people who won’t be paying your bills.
The goal is to build a life your family can actually afford, enjoy, and sustain.
This Memorial Day, America will still travel. The roads will still be full. The airports will still be crowded. The beaches will still be busy. The pictures will still be posted.
But underneath it all, millions of families will be carrying something heavier than luggage.
They’ll be carrying financial pressure.
And that’s why this moment matters.
We can honor the meaning of Memorial Day by remembering those who gave everything for our freedom. And we can honor our own families by learning how to build the kind of financial freedom that lets us live with less fear and more confidence.
Freedom has always carried a price.
Some paid it with their lives.
The rest of us should not waste ours living financially uneducated, overextended, and trapped by decisions we didn’t fully understand.
This summer, make the memories.
Take the trip if it fits.
Enjoy the cookout. See the family. Watch the fireworks. Walk the beach. Sit by the lake. Be grateful for the country, the sacrifice, and the people you love.
But don’t confuse spending with freedom.
Real freedom is knowing how money works.
Real freedom is making decisions with your eyes open.
Real freedom is building a future where your family doesn’t have to borrow tomorrow to enjoy today.
That’s the kind of freedom worth teaching.
That’s the kind of freedom worth protecting.
And that’s the kind of freedom every American family deserves.
Tom Mathews, CFEd®
Money Speaks
Why Financial Literacy Is the New Leadership Imperative
Money is never quiet. Money is never silent.
It speaks in the choices people make under pressure. It speaks in the goals they postpone, the risks they take, the debt they normalize, the opportunities they miss, and the legacy they either build or leave behind. It speaks in a young family living paycheck to paycheck with two incomes. It speaks in a successful professional who earns well but still feels financially exposed. It speaks in the retiree who worked hard for decades yet wonders if the money will last. Money is always talking. The real issue is whether we understand its language.
That’s why financial literacy is not a side issue. It’s not an elective. It’s not “nice to have.” It’s leadership material. Because when people understand money, they make better decisions. They ask better questions. They avoid more traps. They gain more confidence. And when enough people understand money, families get stronger, communities get healthier, and futures get bigger.
We live in a world where people are taught how to pass tests, but not how money works. That gap has a price. It shows up in stress, confusion, bad financial products, costly debt, weak planning, and dreams that shrink under the weight of avoidable ignorance. Financial illiteracy doesn’t just cost money. It costs peace. It costs time. It costs dignity.
Financial Education Is the Beginning, Not the Finish
There’s an important distinction that leaders need to make clear: being financially educated isn’t the same as being financially literate.
Financial education is exposure. Financial literacy is application. Education means you’ve heard the concepts. Literacy means those concepts now shape your behavior. Education tells you what compound interest is. Literacy causes you to respect it. Education introduces the idea of budgeting. Literacy changes how you spend on Tuesday afternoon, not just what you believe on Sunday morning. Education explains debt. Literacy changes the way you borrow, save, protect, and plan.
That distinction matters because information alone does not change lives. Action does. One of the clearest themes running through these books and materials is that knowledge is powerful, but disciplined action is what moves people forward. In other words, it’s not enough to know better. You have to do better. That’s where leadership begins: not in inspiration alone, but in execution.
Money Tells the Truth
Money has a way of exposing reality.
It reveals whether people have a plan or are just hoping things work out. It reveals whether they understand the cost of delay. It reveals whether they are making decisions based on knowledge or emotion. It reveals whether they are building wealth intentionally or drifting financially with no clear direction. You can fake confidence in a lot of areas. Money is harder to fool.
And money speaks with unusual honesty because it speaks in outcomes. It doesn’t care about good intentions. It responds to habits, time, discipline, and understanding. That’s one reason financial literacy is so empowering. It gives people a way to interpret what money is saying before the consequences become severe. It gives them a framework for making informed decisions instead of expensive guesses.
The Rule of 72: One Simple Formula, One Stunning Wake-Up Call
If you want proof that money speaks clearly, look no further than the Rule of 72.
The Rule of 72 is one of the simplest and most revealing formulas in personal finance. Divide 72 by your rate of return, and you get an estimate of how many years it takes for money to double. That simple bit of math carries a powerful message: small differences in rates create massive differences in long-term outcomes.
That means money isn’t just speaking. It’s warning. It’s teaching. It’s exposing.
At low rates, money barely moves. At better rates, it compounds. At high-interest debt levels, it turns vicious. The same principle that can quietly build wealth over time can also quietly wreck a family’s future when used against them through credit cards, loans, and bad financial habits. Financially aware people learn to put compounding to work for them. Financially unaware people often discover, too late, that compounding has been working against them all along.
This’s why financial literacy changes lives. It helps people see the hidden math behind their choices. It gives them a practical lens for evaluating accounts, investments, debt, and time. It replaces vague optimism with measurable understanding. That shift alone can alter the direction of an entire life.
Leadership Means Replacing Confusion With Clarity
Real leadership doesn’t just motivate people. It equips them.
Leadership is often described as influence, vision, and character, and it’s all of those things. But in the context of financial literacy, leadership means something even more practical: it means helping people move from confusion to clarity and from clarity to action. It means taking what feels complicated and making it usable. It means teaching people how to think, not just what to think.
The strongest leaders in these materials aren’t presented as title-holders. They’re builders. They take ownership. They create systems. They model discipline. They don’t point fingers at the problem; they step into it. They understand that if people are going to lead their financial lives well, someone has to first teach them the rules of the game.
Leadership also means refusing to let people stay stuck in financial passivity. Too many people have been conditioned to believe that money is too complex, the system is too stacked, or somebody else will eventually handle it. Leaders break that spell. Leaders show people that while no one can master everything overnight, anyone can begin learning how money works and start making better decisions immediately.
Financial Literacy Protects More Than Wallets
Financial literacy protects people from exploitation.
That may be one of the most important points in all of this. When people don’t understand money, they’re easier to mislead. They’re more likely to accept weak rates, bad terms, expensive products, unnecessary fees, and financial arrangements that benefit everyone except them. Ignorance is expensive, and in many cases it’s profitable for somebody else.
But when people become financially literate, the power dynamic changes. They stop being passive consumers. They become informed decision-makers. They recognize when something doesn’t add up. They understand the value of comparison, context, long-term thinking, and trusted professional guidance. Education does not make people cynical. It makes them harder to exploit.
That’s one reason this work carries so much human value. Financial literacy is not merely about accumulating more. It’s about living with more confidence, more control, and more dignity. People who understand money can face life with less fear. They can make decisions with more calm. They can build with more purpose.
The New Standard of Leadership: Teach It Forward
The old model said financial knowledge belonged to the few. The new model says it needs to reach everyone.
That’s why this mission matters so much. The idea of bringing financial education from Wall Street to Main Street is powerful because it frames money knowledge as something practical, accessible, and needed by ordinary people living real lives. Families don’t need more jargon. They need truth explained clearly. They need principles they can apply. They need trusted people who care enough to teach.
The leadership lesson here is simple: if you know something that can help people build a better future, you have a responsibility to teach it forward.
That applies to parents. It applies to business owners. It applies to financial professionals. It applies to educators. It applies to anyone who has learned even a little more about money than the average person around them. Leadership multiplies when knowledge is shared. Influence compounds when clarity spreads.
This is also where teamwork enters the picture. No meaningful movement happens alone. Financial literacy grows fastest when people fly in formation, align around a mission, and help one another rise. The most powerful impact is rarely solo impact. It’s compounded impact.
A Better Future Starts With Better Decisions
The future belongs to people who can interpret what money is saying and respond wisely.
In a time of rapid change, economic pressure, and a massive transfer of wealth, financial literacy is no longer optional. It’s a modern survival skill. More than that, it’s a modern leadership skill. People who understand money can make wiser decisions for themselves, their families, their businesses, and the people they serve.
And the path forward doesn’t have to be complicated. Learn the basics. Respect time. Understand compounding. Reduce costly debt. Build better habits. Work with a financial professional you trust. Ask better questions. Keep learning. Then teach someone else. That’s how literacy becomes culture. That’s how knowledge becomes momentum.
Listen to Money Before It Has to Shout
Here’s the truth: money will keep speaking whether you listen or not.
It will whisper through opportunity. It will warn through delay. It will reward understanding. It will expose neglect. And eventually, if ignored long enough, it will shout through consequences.
So don’t wait for the shout.
Learn the language now. Raise your standards now. Lead your financial life on purpose now. If you’re financially educated, take the next step and become financially literate. Turn knowledge into behavior. Turn behavior into confidence. Turn confidence into leadership. And once you do, help somebody else do the same.
If you want to know where you stand today, take the Financial Literacy Quiz. Find out what you know. Find out what you don’t know yet. Then go to work on it. Because your future will be shaped, in part, by how well you respond to what money has been saying all along.
Tom Mathews
The Golden Ratio and You

Why WealthWave's Pay System Is Built on Nature's Most Powerful Law
Nature doesn't guess. It doesn't improvise. It builds according to a hidden code, a mathematical ratio so precise, so universal, that you'll find it in the spiral of a galaxy, the seed arrangement of a sunflower, the dimensions of the Parthenon, and the design of the iPhone you're holding right now.
That ratio is φ or Phi, also known as the Golden Ratio. Approximately 1.618.
And it's not a coincidence that WealthWave's entire compensation system is built around it.
Nature's Blueprint
The Golden Ratio emerges when you divide a line into two parts, a longer segment and a shorter one, in such a way that the longer part divided by the shorter part equals the longer part plus the shorter part divided by the longer part. The answer is always 1.618.
That sounds like math class. Here's what it actually means.
Leonardo da Vinci used it in the Mona Lisa. The architects of the Parthenon encoded it in every column. Sunflowers arrange their seeds in Fibonacci spirals, the numerical sequence that produces the Golden Ratio, to pack the maximum number of seeds into the minimum space. Hurricanes form in the same spiral. So do galaxies. So does the nautilus shell.
The universe, it turns out, has a preferred way of organizing growth. And that preference is the Golden Ratio.
The question I asked wasn't whether this principle was real. It clearly is. The question was: what would happen if we built a business around it?
The 65/35 Principle
WealthWave's compensation model is a direct application of the Golden Ratio. Specifically, the two-thirds to one-third rule that the ratio produces.
Here's how it works:
65% of compensation flows to the base agency. The producers and developing leaders who are doing the daily work of building clients, writing business, and creating teams.
35% of compensation flows upward to leadership. The overrides and bonuses that compound as you build, develop, and duplicate leaders beneath you.
This isn't an arbitrary split. It's the same proportion you find in nature's most efficient systems. The 65% creates the foundation, the deep roots, the wide base, the fertile ground where production happens and new leaders grow. The 35% creates the reward for building something that outlasts you.
And here's the part that separates this from every other pay system in financial services: the 35% can compound without limit. There's a ceiling on what you can earn by selling. There's no ceiling on what you can earn by building.
Two Paths. One System.
Most compensation systems in this industry force a choice: produce or manage. Earn now or earn later. Build a book or build a team.
WealthWave's Golden Ratio model refuses that tradeoff.
The 65% rewards you for what you do today. The 35% rewards you for what you build over time. Both run simultaneously. Both grow together. The producer and the leader aren't in competition, they're in symbiosis. Just like the sunflower, where each seed supports the spiral that makes room for the next one.
This is why WealthWave leaders can genuinely say: the bigger your team gets, the better it is for everyone on it. That's not a tagline. It's mathematics.
The Fibonacci Spiral in Action
The Fibonacci Sequence 0, 1, 1, 2, 3, 5, 8, 13, 21, 34... is the numerical engine behind the Golden Ratio. Each number is the sum of the two before it. As the sequence grows, the ratio between consecutive numbers converges on 1.618.
When you draw this sequence as squares and trace a curve through them, you get the Fibonacci spiral. The same shape as a hurricane, a galaxy, a nautilus shell.
Now picture your WealthWave organization as that spiral. Each new leader you develop is a new square added to the pattern. The spiral doesn't change shape as it grows, it just gets bigger, while maintaining the same proportions. Your core culture, your teaching-first philosophy, your mission stays intact at every level of scale.
That's not accidental. That's architecture. The Golden Ratio is how you build something that grows without losing itself.
Why This Matters to You Right Now
You're not just building a business. You're building a system that mirrors the most successful growth pattern in the known universe.
Every family you teach, before you ever ask for anything, is a seed in the spiral. Every leader you develop is a new square in the Fibonacci sequence. Every promotion on your team makes the structure stronger, not weaker. The 65% keeps energy and momentum at the base. The 35% keeps leaders invested in building the next wave.
This is why WealthWave doesn't produce order-takers. It produces builders.
The two-thirds to one-third rule isn't just how we pay people. It's how we think about growth, leadership, and the relationship between individual success and organizational health. It's the reason a new associate and a 30-year veteran can sit in the same room and both feel like the system is working for them, because it is.
The Pattern You're Already Part Of
The Golden Ratio appears wherever sustainable growth exists. In nature. In art. In the greatest companies ever built. In the spiral of a hurricane and the seed pattern of a sunflower.
And in WealthWave.
When you recruit someone who then builds a team of their own, you're not just duplicating effort, you're extending the spiral. When your leaders promote, their success feeds yours, and yours feeds theirs. When the base agency grows, the leadership tier compounds. It's the same pattern, at every level, endlessly repeating.
Phi doesn't know the difference between a seashell and a sales organization. It just knows harmony. It knows proportion. It knows that the structures built to its specifications last, and the ones that aren't don't.
WealthWave was built to last. So were you. The Golden Ratio is why.
Ownership vs. Income: What George Lucas Can Teach Us

A Serious Lesson Behind a Cultural Phenomenon
Every May 4th, millions of people think about Star Wars. They remember the characters, the music, the story, and the world George Lucas created. But beneath the cultural phenomenon is a serious financial lesson.
George Lucas did more than create one of the most successful film franchises of all time. He created something he could own.
That distinction matters.
Income is what you receive for work performed. Ownership is what can continue to grow after the work has been done. Income pays you for your time, talent, effort, or production. Ownership gives you a stake in something with the potential to expand, multiply, and create value over time.
That is one of the most important financial literacy lessons anyone can learn.
George Lucas Built More Than a Movie
Before Star Wars became a global phenomenon, George Lucas was building more than a film. He was building a company, a system, and a future he could have greater control over.
Most people are taught to think primarily in terms of income. Get a job. Earn a paycheck. Work more hours. Get a raise. Find a better position. Those are not bad things. Income is necessary. But income alone is limited by time, role, contract, employer, and circumstances.
Ownership asks a different question.
What are you building?
That question changes everything.
When Star Wars: A New Hope was being developed, Lucas needed more than actors, sets, and a script. He needed technology, creative infrastructure, visual effects, sound design, and a production system that could bring his vision to life.
He did not simply rent every piece of the process from someone else. He built capability. He invested in tools, teams, and systems. Over time, those capabilities became valuable in their own right.
Eventually, Lucasfilm, Star Wars, Industrial Light & Magic, and Skywalker Sound became part of one of the most significant entertainment acquisitions in modern history when Disney purchased Lucasfilm in 2012 for approximately $4.05 billion.
That number is not only a Hollywood headline. It is a financial literacy lesson.
George Lucas did not merely get paid for directing a movie. He built an asset.
That is the difference between income and ownership.
Why This Matters to WealthWave
This is one reason the Star Wars story connects so powerfully to the WealthWave opportunity. WealthWave exists because millions of families have never been taught how money really works. They know how to work for income, but many have never been taught how wealth is built, protected, transferred, or multiplied.
They know what a paycheck is, but they may not understand the role of assets, compound interest, debt, protection, taxation, ownership, or long-term strategy.
Financial literacy changes the questions people ask.
Instead of only asking, “How much do I make?” people begin asking:
What do I own?
What is growing?
What is costing me?
What is protecting my family?
What is my money doing when I am not actively working?
What am I building that can last?
For WealthWave, this is where the business opportunity becomes meaningful.
From Consumer to Educator
The WealthWave opportunity is not simply about adding another activity to an already busy life. It is about stepping into a different role.
Instead of only being a consumer of financial products, services, and systems, a person can become an educator.
Instead of only learning for themselves, they can help others learn.
Instead of only earning income from their own labor, they can begin building a business around a mission: teaching people how money works.
That matters because financial illiteracy is not a small problem. It affects families, workers, students, business owners, retirees, and entire communities. It shows up in debt, confusion, delayed decisions, missed opportunities, and fear about the future.
Many people are not unintelligent. They are uninformed.
They were never taught.
WealthWave gives people a way to participate in solving that problem.
Ownership Requires Work
The business is not automatic. It does not come with guaranteed income. Like any business, results depend on effort, consistency, skill development, licensing where required, leadership, market conditions, and the ability to serve people well.
But the principle remains important: there is a difference between only earning income and building something you own.
Many people spend their lives renting their time to someone else. They may do excellent work. They may become skilled, respected, and well paid. But if the income stops when the work stops, they are still tied to the limits of active labor.
A business opportunity invites a person to think differently.
Can I build a client base?
Can I build trust?
Can I build a team?
Can I build a reputation?
Can I build a system of education and service?
Can I create value that reaches beyond my own household?
That is not just a financial question. It is a life question.
Star Wars Became an Expanding Asset
George Lucas’ story is useful because it shows the power of creating something with long-term value. Star Wars became more than a film. It became a world that expanded into sequels, prequels, television, books, games, consumer products, theme park experiences, visual effects, sound innovation, and generations of fans.
That is what ownership can do. It can expand beyond the original act of creation.
For WealthWave, the lesson is not that everyone should become George Lucas. The lesson is that people need to understand the difference between being paid once and building something with ongoing value.
A person can work a job and earn income.
A person can also build a business, a team, a platform, a reputation, a body of knowledge, and a client-centered mission.
Those are different paths.
The WealthWave Opportunity Is Built Around Education
The WealthWave opportunity is built around a simple but powerful idea: financial education can become both a mission and a business.
When someone learns how money works, they are better equipped to make decisions for their own family.
When they learn how to teach those concepts to others, they can become part of a larger movement.
When they build a business around that education, they are no longer only consuming knowledge. They are helping distribute it.
That is ownership thinking.
It is the shift from “What can I earn?” to “What can I build?”
It is the shift from “Who will teach me?” to “Who can I teach?”
It is the shift from “I need opportunity” to “I can become part of creating opportunity for others.”
A Serious Opportunity for a Serious Problem
That is why the WealthWave business opportunity should be understood through the lens of financial literacy, not hype.
The real value is not in promising easy money. The real value is in helping people see that they have options.
They can learn. They can grow. They can become licensed where required. They can build credibility. They can use books, tools, classes, conversations, and technology to reach people who need help understanding basic money concepts.
The opportunity is serious because the need is serious.
Families need education before they make major financial decisions. Young adults need education before debt shapes their lives. Parents need education before they try to guide their children. Communities need education before another generation repeats the same mistakes.
WealthWave’s mission is to bring that education to the people who need it.
Income Helps You Survive. Ownership Helps You Build.
For the person who chooses to build the business, the question becomes: Do I only want income, or do I want to build ownership around a mission I believe in?
Income helps you survive.
Ownership helps you build.
Income can meet today’s needs.
Ownership can shape tomorrow’s possibilities.
Income is important, but ownership can create legacy.
The Real Lesson of May 4th
George Lucas built a story world that changed entertainment. WealthWave is building a financial education movement designed to change families. The industries are different, but the principle is the same: long-term value belongs to those who understand what they are building.
This May 4th, the real lesson is not about fantasy. It is about financial literacy.
Wealth is rarely created by income alone. It is created when people learn how value works, how ownership works, how systems work, and how a mission can become a business.
That is the opportunity in front of WealthWave builders.
Not just to earn.
To educate.
To build.
To own.
To help create a future where more families understand how money works.
From Revolution to Revolution

Our Vision and Mission Grew Into Something Bigger
We've always been revolutionaries.
In the 1990s, when we were building our original company, we stood in front of families and told them something the financial industry didn't want them to hear: you deserve access to the same products the wealthy have always had.
Investment and insurance had finally been combined. The performance possibilities of professional management paired with the tax advantages of annuities and life insurance. For the first time, families who had been locked out of sophisticated financial strategies could participate. It was a genuine breakthrough.
Our Original Vision: To Lead the Investment Revolution
Our Original Mission: Help Families Become Financially Independent
We did it with products, services, and a business opportunity that gave people two paths to a better life. Make more income. Be smarter with the money you already had. For thousands of families, it worked. It changed lives. It built futures.
We were proud of that. We still are.
BUT REVOLUTION DOESN'T STAND STILL
The world kept moving. The products got better. Indexed products arrived, bringing with them something that had not existed before: guarantees. Growth potential with no market risk. The ability to say to a family, “You can participate in market gains and never lose what you've built.” That is a revolution within a revolution.
And yet, something kept nagging at us.
The products were powerful. The opportunity was real. But we kept sitting across from families who did not know what compound interest was. Who had never heard of the Rule of 72. Who were making decisions about debt, savings, and retirement, decisions that would echo for decades, based on nothing more than habit and hope.
The products were not the problem.
The problem was that nobody had ever taught these families how money actually works.
Not their schools. Not their banks. Not the financial industry that was supposed to serve them. Financial literacy had been quietly, systematically withheld from the people who needed it most. The result was a nation of families working hard, doing their best, and still falling behind. Not because they lacked effort. Because they lacked education.
That was the real enemy. And once we saw it clearly, we could not unsee it.
THE EVOLUTION OF OUR VISION
Our Updated Vision: Lead the Financial Literacy Revolution
We updated our compass. Notice what changed, and what did not. The word Revolution stayed. We have always been willing to challenge the status quo, to go where the industry would not go, to stand in living rooms and community centers and say things that disrupted comfortable thinking. That has not changed. It never will.
What changed is what we are revolutionizing.
In the 1990s, we were revolutionizing access, getting families into products they had been excluded from. Today, we are revolutionizing understanding, making sure that when families make financial decisions, they actually know what they are doing and why.
We also added something to the promise. Through education and access to innovative products, we help people live with confidence, free from the fear of outliving their money.
That phrase, free from the fear of outliving their money, is not marketing language. It is the deepest financial fear millions of Americans carry quietly every single day. Not the fear of a bad quarter. The fear that after a lifetime of work and sacrifice, the money runs out before they do.
That fear is almost entirely preventable. With education. With planning. With the right financial strategy put in place early enough.
Eliminating that fear at scale, for millions of families, is what we are here to do.
THE EVOLUTION OF OUR MISSION
Our Updated Mission: Teach More People How Money Works
More than any company in history, we equip people to make informed financial decisions. We teach first. We serve only when asked.
The original mission was about outcomes: helping families become financially independent. That was the destination. Noble. True. And we achieved it for countless families.
The updated mission is about the method, because we learned something profound along the way.
You cannot sustainably help a family reach financial independence if they do not understand the principles that create and protect wealth. Products without education produce dependency. Education without products produces awareness without action. But education first, followed by the right products and the right opportunity, offered only when the family is ready and asks, produces something entirely different.
It produces empowered people who own their financial future.
We teach first. We serve only when asked. Those nine words are a complete philosophy. They are the most counter-cultural thing we say, and the most important. The financial industry leads with the product and works backward to justify it. We lead with knowledge and earn the right to serve.
When a family truly understands how money works, they lean forward. They ask for help. And when they ask, we are there, with a business opportunity that can change their income, and with products that have only gotten better. Managed money. Tax-advantaged strategies. And now indexed products that offer growth with guarantees, the best of both worlds.
The opportunity has not shrunk. It has grown. The products have not weakened. They have strengthened. The business model has not changed. It has been clarified.
What changed is the foundation everything rests on: education first, always.
THEN AND NOW. ONE CONVICTION, GROWN STRONGER
Two revolutions. Thirty-plus years apart. Both born from the same conviction: families deserve better than what the financial industry has given them.
But today's Vision and Mission are more powerful. More expansive. And they apply to everyone.
The original mission was built around a specific breakthrough, products that had been kept from ordinary families. It was transformational for its time, and it still is. But it required the right product fit, the right moment, the right family profile.
Today's mission has no such limits. Financial literacy belongs to everyone. The Rule of 72 applies to everyone. The fear of outliving your money is felt by everyone. And the simple, radical act of sitting across from a family and teaching them how money works, before asking for anything in return, is available to every leader, in every market, at every level, starting today.
The Vision and Mission we carry now do not narrow our reach. They expand it beyond anything we imagined in 1991.
WHY THIS MATTERS TO YOU AS A LEADER
You are not selling products. You are not recruiting prospects. You are leading a revolution, the same one we started in the beginning, now grown into something larger and more powerful than we imagined then.
The tools and technology are better. Indexed products give you guarantees to offer families that did not exist a generation ago. The content is better. The MoneyBooks series, HowMoneyWorks.com, the Financial Literacy Quiz, WealthWaveONE. We have built an education infrastructure that no other financial company on earth has matched. The moment is bigger. $124 trillion in generational wealth transfer is already in motion, and the families who understand money will be the ones who keep it.
And the mission is clearer than it has ever been.
We teach first. We serve when asked. We change lives.
That is not new. That is who we have always been, just with thirty more years of proof that it works.
The Financial Literacy Revolution is not coming. It is here. And we are leading it.
Tom Mathews
Rich Starts in the Mind
Why Financial Education Creates the Mindset That Can Lead to Lasting Wealth
Most people think being rich starts with money.
It doesn’t. It starts with mindset.
Long before someone builds a strong income, grows investments, or achieves financial independence, they first develop the ability to think differently about money. They begin to see opportunity where others see obstacles. They take responsibility where others assign blame. They pursue education where others wait for rescue.
That’s where wealth begins.
“A wealthy life starts with a wealthy mindset, and a wealthy mindset starts with financial education.”
Having money doesn’t automatically make someone wealthy. We’ve all seen people come into money and lose it. A bonus gets spent. An inheritance disappears. A windfall gets wasted. Why? Because money without understanding rarely lasts.
Real wealth is not just about possessions. It’s about capability.
It’s the ability to earn, manage, protect, grow, and reproduce money over time.
That ability comes from financial literacy.
At WealthWave, that’s the heart of what we teach. Financial education changes the way people think. It gives them the tools to make sound decisions. It helps them avoid costly mistakes. It gives them a plan. And when people begin to understand how money works, they stop reacting emotionally and start acting strategically.
That shift changes everything.
“The first sign of wealth is not a big bank account. It’s better thinking.”
A wealthy mindset is built on responsibility. It says, “My future is up to me.” It doesn’t blame the economy, successful people, the government, or bad luck. It asks better questions. It looks for better answers. It becomes teachable, disciplined, and intentional.
A poor mindset does the opposite. It waits. It complains. It criticizes. It believes someone else is supposed to fix the problem. And because it avoids learning, it stays stuck.
That’s why financial literacy matters so much. It teaches people how to move from confusion to confidence. It teaches them how to replace guesswork with knowledge. It teaches them that money is not just something you earn—it’s something you must understand.
Without education, people are vulnerable. They can be misled, exploited, and trapped in cycles of debt, fear, and short-term thinking. But with education, they begin to make decisions from a position of clarity and strength.
“Financial education is the bridge between working hard and actually getting ahead.”
This is one of the great truths in life: people with the right mindset often build money, while people with the wrong mindset often lose it.
Why?
Because a wealthy mindset values growth.
It values learning new skills, improving decision-making, delaying gratification, and thinking long-term. It understands that discipline today creates freedom tomorrow. It knows that building wealth is usually not dramatic—it’s consistent.
That’s why someone can have very little money today and still be on the road to wealth. If they are learning, growing, and developing financial intelligence, they are already moving in the right direction.
On the other hand, someone can have money today and still be financially poor in their thinking. If they lack discipline, lack understanding, and lack a plan, their money is usually temporary.
“Money follows value, discipline, and understanding. It rarely stays where those are absent.”
As leaders, this is a message we need to keep front and center.
Our mission is bigger than helping people earn more. Our mission is to help people think better. Because when people think better about money, they live better. They protect their families better. They prepare for retirement better. They avoid exploitation better. They build a future with greater confidence and less fear.
That’s the power of financial education.
It turns consumers into learners.
It turns earners into investors.
It turns families from financially exposed to financially prepared.
And most importantly, it turns hope into a plan.
This is why I’ve always believed that financial literacy is one of the most important forms of leadership in America today. When you teach people how money works, you are not just giving them information. You are giving them a new lens for life. You are helping them see what is possible. You are helping them take control of a part of life that too many people have been taught to fear.
“When people understand money, they stop living by accident and start living by design.”
A wealthy mindset also understands that success is built, not handed out.
It knows that growth takes time.
It respects the process.
It understands that reading, learning, saving, investing, and staying consistent may not look exciting in the moment, but over time those habits create extraordinary results.
That’s why the path to wealth is really a path of education first. Not because education alone guarantees success, but because without it, success is hard to recognize, harder to build, and even harder to keep.
The families we serve don’t just need more income. They need more understanding.
They need to know how compound interest works.
They need to know the Rule of 72.
They need to know the difference between saving and investing.
They need to know how debt steals momentum.
They need to know how to protect what they build.
They need to know how money really works.
That is how a wealthy mindset is formed. And once that mindset is in place, better financial behavior follows. Better behavior leads to better results. Better results, repeated over time, lead to wealth.
“Wealth is not built by chance. It is built by educated decisions made consistently over time.”
So when we talk about being rich or poor, let’s raise the conversation.
Let’s not reduce it to what someone has in their account today.
Let’s talk about how they think.
Let’s talk about what they know.
Let’s talk about whether they are growing, learning, and becoming more capable.
Because rich starts before the money shows up.
It starts with mindset.
It starts with discipline.
It starts with responsibility.
And it starts with financial education.
That’s why what we do matters.
“The richest person in the room is often the one who understands money best.”
We’re helping people become the kind of person who can build wealth, keep wealth, and use wealth wisely. That’s not just good for their bank account. That’s good for their family, their future, and their legacy.
The $1.83 Trillion Wake-Up Call

What America’s Student Loan Crisis Means for Every Family
“An investment in knowledge pays the best interest.”
Benjamin Franklin
Franklin said that nearly 300 years ago. He was right then. He’s even more right now because the opposite is also true: a lack of knowledge about debt can cost you everything.
The Number That Should Stop You Cold
Right now, as you read this, American borrowers collectively owe $1.83 trillion in student loan debt. Not $1 billion. Not $100 billion. $1.83 trillion, a number so large the human brain struggles to process it.
Let’s make it real. If you stacked $1 trillion in $100 bills, the pile would reach 630 miles into space. America’s student loan debt towers 80% higher than that. Every single day.
This is not a distant policy debate. It is a personal financial crisis that lives inside 43 million American households, inside the lives of real people who were handed a diploma in one hand and a debt sentence in the other, often without ever being taught how either one actually worked.
The Real Portrait of a Borrower
Here’s what the average person carrying student loan debt looks like in 2026:
They owe $39,547 in federal loans alone. When private loans are added, that figure climbs to $43,333 per borrower. That is not a car payment. That is a second mortgage, except with no house to show for it and no equity building underneath it.
They graduated with a degree, a dream, and a payment book. Many of them were 17 or 18 years old when they signed those loan documents, people who could not legally rent a car but were handed six-figure obligations and told to sign on the dotted line.
No financial education required. No “how money works” class as a prerequisite. Just sign here, show up in September, and figure it out later.
And now, later has arrived.
The Default Cliff: Where We Stand in 2026
The numbers coming out of 2025 and early 2026 are not just alarming. They are historic.
Nearly 25% of all federal student loan borrowers with a payment due are now behind. That is one in four. In 2019, that number was 9%. The delinquency rate has nearly tripled in six years.
Around 7.9 million borrowers entered delinquency in the first three quarters of 2025 alone. And the Education Department confirmed that by the end of 2025, 7.7 million borrowers had defaulted on $181 billion in federal loans, with another 3 million at least three months behind.
That means roughly 1 in 4 of the 43 million federal loan holders are seriously behind on their payments, the highest combined rate of delinquency and default since the government began tracking the data.
In Louisiana and Mississippi, the delinquency rate among borrowers with payments due has surged to nearly 40%. Black borrowers are carrying the heaviest burden. More than 48% of Black student loan borrowers were past due in the third quarter of 2025, compared to 20% of white borrowers.
Think about those numbers. Nearly half of an entire demographic of borrowers is behind. Not because they are irresponsible. Because no one ever sat them down and showed them how money works.
The Ripple Effect: It’s Bigger Than a Monthly Payment
Here’s what the data does not capture: the cost of a student loan is not just the monthly payment. It is everything the payment crowds out.
When the median American household with a family of four and income of $81,000 faces a potential jump from $36 per month to $440 per month in student loan payments due to policy shifts, that is not a line-item adjustment. That is the difference between saving for retirement and not. Between building an emergency fund and living without a safety net. Between investing early, when compound interest is your greatest ally, and investing never.
Around 2 million student loan borrowers have already seen their credit scores drop, with an average fall from 680 to 580, moving them from “good credit” to a category lenders treat with suspicion. That affects their ability to buy a home, purchase a vehicle, start a business, or simply borrow at a reasonable rate.
A Fidelity 2026 State of Student Debt report found that nearly 1 in 3 borrowers currently paying off loans are making tradeoffs between loan payments and covering basic needs. That is not a debt problem. That is a survival problem.
Meanwhile, the Rule of 72 tells us that money invested wisely can double. But money trapped in high-interest debt follows the same math, only it is doubling against the borrower. Every dollar not invested in your 20s does not just stay flat. It costs you the compound growth that would have funded your future.
This is what financial ignorance looks like at scale.
How Did We Get Here? The Road Paved With Good Intentions
The federal student loan program launched in 1958 under the National Defense Education Act. The idea was sound: open the doors of higher education to more Americans. And it worked. College enrollment surged over the following decades.
But somewhere along the way, the system lost its compass. The cost of college skyrocketed. The availability of loan money made colleges less price-sensitive and students less cost-aware.
By June 2010, student loan debt in America had surpassed total credit card debt. By late 2015, it crossed $1.3 trillion. By 2021, $1.73 trillion. By 2025, $1.833 trillion, and still climbing, having grown another $54 billion in 2025 alone.
Every step of the way, one critical ingredient was missing: financial education.
Students were not taught how compound interest works. Families were not shown how to calculate return on investment for a degree choice. No one explained that a $60,000 education loan at 7% interest, on a 10-year repayment plan, results in paying back nearly $84,000 total, before life’s other expenses ever arrive.
The machine ran. And millions of people got caught in it, not because they were foolish, but because they were uninformed. That is not their failure. That is a system failure. And it is one that financial education is specifically designed to fix.
The Financial Literacy Connection: The Missing Piece of the Puzzle
Here’s the truth WealthWave was built around: financial mistakes are not inevitable. They are predictable. And they are preventable with education.
Ask yourself:
How many of those 43 million borrowers understood, before they signed, the total cost of their loans?
How many compared their expected starting salary in their chosen field against their projected monthly debt payment?
How many knew the difference between subsidized and unsubsidized loans, or understood that interest could capitalize while they were still in school?
The answer is sobering.
Only 27% of Americans passed a basic financial literacy test in 2025. The average score on a national personal finance assessment was just 49% correct.
We are a nation of financially unprepared people making some of the largest financial decisions of their lives at age 17.
The student loan crisis is not simply the result of predatory lending or political failure, though both play roles. At its root, it is the direct consequence of a financial literacy emergency that has been building for decades.
This is why the work we do at WealthWave is not optional. It is urgent. It is a matter of financial life and death for families across this country.
What Financial Education Actually Changes
Financial literacy is not theory. It is armor.
When someone understands compound interest, they know why paying off high-interest debt aggressively is the smartest investment they can make right now.
When someone understands the time value of money, they know that $200 invested at 25 is worth far more than $400 invested at 45, and that every month of delay has a real dollar cost attached to it.
When someone understands income-driven repayment options such as IBR, PAYE, ICR, and SAVE, they do not fall into default out of ignorance. They make an informed choice.
When someone understands loan amortization, they know that the minimum payment keeps them trapped while extra principal payments help break the cycle.
When someone understands net worth versus income, they stop confusing a good salary with financial security and start building actual wealth.
These are not complicated concepts. They require a teacher. They require an educator who cares enough to sit down with a family and say, “Let me show you how this actually works.”
That is exactly what WealthWave leaders do every day.
The Call to Action for Every WealthWave Leader
The student loan crisis is a mirror. Look at it directly.
More than 10 million Americans are either in default or dangerously close. Millions more are watching their credit scores collapse. Families are choosing between their loans and their groceries, not because they do not want to do the right thing, but because no one ever showed them what the right thing looks like.
Every family in your community deserves better. Every young person about to sign a loan document deserves to understand what they are signing. Every 35-year-old drowning in debt deserves to know there are options: income-driven plans, forgiveness timelines, refinancing strategies, and the guidance of a financial educator who can help them chart a path forward.
The debt is real. The crisis is real. But so is the solution.
Knowledge changes everything. It always has. It always will.
A financially educated America looks different. It looks like people who borrow with intention, repay with strategy, invest early, retire with dignity, and pass that wisdom on to the next generation.
That future does not build itself. We build it, one conversation, one family, one community at a time.
Your Next Steps, Right Now
Share this article with every WealthWave leader on your team and every prospect in your pipeline.
Use the student loan statistics in your next presentation. These numbers open eyes and open doors.
Start the financial literacy and Rule of 72 conversation before the debt conversation. Prevention beats recovery every time.
Visit HowMoneyWorks.com and put the tools in someone’s hands today.
Take the Financial Literacy Quiz at TakeTheFLQ.com and challenge your contacts to do the same. Awareness is the first step toward change.
“The more that you read, the more things you will know. The more that you learn, the more places you’ll go.”
Dr. Seuss
The student loan crisis did not happen overnight. It was built one financially uninformed decision at a time. The solution works the same way, one educated decision at a time.
Let’s get to work.