





Conducting a Leadership Team
How Leaders Perform Their Best
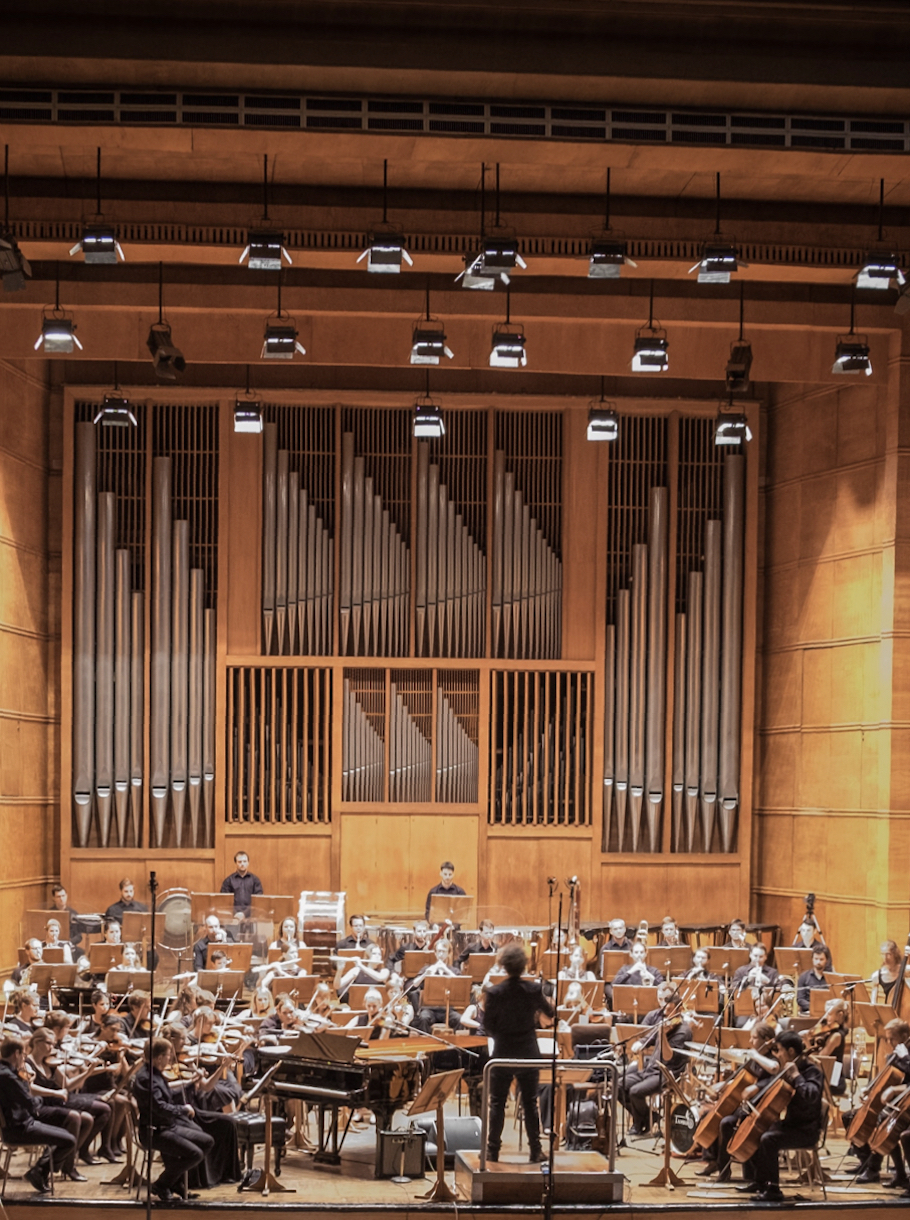
Leading a successful team, much like conducting a world-class orchestra, demands a unique blend of vision, coordination, and the ability to turn away from the crowd to focus on the harmonious execution of a grand plan. In the realm of leadership, success is not just about individual brilliance but about orchestrating a team to perform at its peak potential.
Like an orchestra without a conductor, a team without a leader can struggle to find direction and synergy. The conductor, armed with a deep understanding of every note in the score and how each instrument contributes to the overall symphony, guides the musicians to create a masterpiece. Similarly, a successful leader recognizes the unique strengths and roles of each team member, aligning them towards a common goal. This alignment is the essence of leadership orchestration.
Turning Your Back On The Crowd
Turning your back on the crowd is a metaphor for the courage and focus required of great leaders and conductors alike. For a conductor, the audience is important, but during the performance, their entire focus is on the orchestra. This is true for leaders as well. While being aware of external expectations and perceptions, a leader’s primary focus should be on their team and objectives. This focus ensures that each team member's contribution is optimized, and the collective effort leads to extraordinary outcomes.
In either case, positioning could allow them to face the audience and performers at the same time, creating a unique dynamic where the leader or conductor becomes a bridge between the performers and the audience. This positioning symbolizes a dual focus: inward towards the team or orchestra to ensure flawless execution, and outward towards the audience or stakeholders to gauge their reactions and adapt accordingly.
Such a stance requires a high level of skill and awareness. For a conductor, it means not only leading the orchestra but also engaging with the audience, creating an immersive experience that transcends mere performance. For a leader, this means balancing internal team management with external stakeholder engagement, ensuring that both the team's and the stakeholders' needs are met and aligned.
Facing Your Team And Engaging The Audience
This dual-facing approach also symbolizes transparency and inclusivity. The audience or stakeholders feel more connected to the performance or process, as they witness the leadership in action. It fosters a sense of trust and involvement, as they see the leader or conductor actively managing and responding to the dynamic environment.
This positioning allows for real-time feedback. For a conductor, the immediate audience reaction can inform subtle changes in the performance, making it more responsive and adaptive. Similarly, a leader who faces both their team and company can quickly gauge the impact of their decisions and strategies, allowing for more agile and responsive leadership.
This unique positioning of facing both the team or orchestra and the audience epitomizes a holistic approach to leadership and conducting. It represents a blend of guidance, engagement, transparency, and adaptability, essential for creating a truly impactful and harmonious experience, whether in music or in leadership.
A great musical score is meticulously composed, with each note and rest crafted for maximum impact. Similarly, effective leaders carefully design their team's strategy, ensuring that each role and task is clearly defined and purposefully assigned. This clarity enables team members to understand their individual responsibilities and how these contribute to the larger objective.
The Importance of Harmony
In both music and leadership, harmony is key. Just as being out of tune in an orchestra can disrupt a performance, misalignment within a team can hinder its success. A skilled conductor uses their baton to guide, pace, and harmonize the orchestra. In the same vein, a leader uses their vision, communication skills, and emotional intelligence to align and motivate their team, turning individual efforts into a cohesive and successful symphony.
The art of leadership, much like conducting an orchestra, is about creating harmony out of diversity, aligning individual talents and roles towards a shared vision. It requires the courage to focus inward, the clarity to define each role, and the skill to harmonize these roles into a cohesive and successful team. Just as the world remembers great conductors for the symphonies they bring to life, great leaders are remembered for the success they orchestrate through their teams.

Embracing Gratitude
The Essence of Living Fully Each Day
As we approach the season of Thanksgiving, a time traditionally reserved for reflecting on our blessings and expressing gratitude, it's an opportune moment to delve into the philosophy of not wasting each day. This week, steeped in appreciation and thankfulness, reminds us of the significance of having a caring heart and grateful mindset. In recognizing the gifts of the present, we find a powerful antidote to the regrets of yesterday and the uncertainties of tomorrow.
Thanksgiving, therefore, is not just a holiday, but a poignant reminder of the maxim, "Yesterday is gone, and tomorrow is uncertain, but today is the youngest you'll ever be again." It underscores the importance of cherishing each day and living in the moment with a spirit of gratitude.
Maximizing Today: Embracing the Present for a Fulfilling Tomorrow
In the transient journey of life, the concept of time becomes both a precious ally and a formidable foe. Often, we find ourselves entangled in the regrets of yesterday or the uncertainties of tomorrow, overlooking the most significant time we possess – today.
Seize the Day: The Power of Now
The present is a treasure trove of opportunities waiting to be explored. Each day is a blank canvas, presenting us with the chance to paint our lives and businesses with new experiences, learning, and growth. The key is to seize these opportunities with all your might.
Embrace Opportunities with Open Arms
“Don't wait until conditions are perfect to begin. Beginning makes the conditions perfect.”
– Bill Mitchell
Overcome Procrastination
"The best way to get something done is to start now.”
– Tom Mathews
Learn from Yesterday, Live for Today
While it's essential to learn from the past, dwelling on it can prevent us from experiencing the present fully. Yesterday's lessons should be stepping stones, not anchors.
Use Yesterday's Lessons Constructively
“Learn from yesterday, live for today, hope for tomorrow.”
– Albert Einstein
Make Today Count: The Urgency of Now
Understanding that tomorrow is not guaranteed instills a sense of urgency to make today count. It encourages us to cherish every moment and make meaningful contributions.
Cherish Each Moment
“The trouble is, you think you have time.”
– Buddha
Today's Actions, Tomorrow's Memories
The actions and decisions we make today shape our future. By making conscious, positive choices, we are essentially scripting our future narratives.
Scripting Your Future
“The future depends on what you do today.”
– Mahatma Gandhi
The Gift of Today
Today is indeed the youngest you'll ever be, and with this comes a unique blend of energy, potential, and opportunity. Let’s not waste the gift of today on the regrets of yesterday or the uncertainties of tomorrow.
Instead, let's make strong, purposeful strides in the present – strides that will echo into our tomorrows, creating a symphony of fulfilled dreams and cherished memories.
In the words of Emily Dickinson, "Forever is composed of nows." Let's make each 'now' count.
Embracing Each Day: The Art of Living in the Moment
As we continue to delve into the importance of not wasting each day, it's imperative to understand the art of living in the moment. This concept, often overshadowed by our busy schedules and long-term plans, is the cornerstone of a fulfilling life.
Mindfulness: The Key to Appreciating Today
Mindfulness is the practice of being fully present and engaged with whatever we're doing, free from distraction or judgment. By being mindful, we open ourselves to the fullness of life in the present moment.
Practice Mindfulness
“Mindfulness isn’t difficult, we just need to remember to do it.”
– Sharon Salzberg
The Role of Gratitude in Valuing Today
Gratitude plays a pivotal role in how we perceive and value our daily experiences. By focusing on what we are thankful for, we shift our perspective from what we lack to the abundance that surrounds us.
Cultivate Gratitude
“Gratitude turns what we have into enough.”
– Thanksgiving Wish
Overcoming the Fear of Missing Out (FOMO)
In a world where social media often dictates our perceptions of a fulfilling life, it's easy to fall prey to the fear of missing out. Embracing today means letting go of the need to be everywhere and do everything.
Let Go of FOMO
“A thousand half-loves must be forsaken to take one whole heart home.”
– Rumi
Creating a Legacy Today
Every action and decision we make today contributes to the legacy we leave behind. By living intentionally and with purpose, we ensure that our legacy is one of positivity and impact.
Live Intentionally
“Carve your name on hearts, not tombstones. A legacy is etched into the minds of others and the stories they share about you.”
– Shannon Alder
The Symphony of Today
It's clear that not wasting each day is about much more than simply being productive. It's about living with intention, practicing gratitude, embracing the present, and understanding the impact of our actions on our future.
As we navigate through the complexities of life, let us remember to cherish and make the most of each day, for it's in these moments that the fabric of a well-lived life is sewn.
In the words of Mary Oliver, "Tell me, what is it you plan to do with your one wild and precious life?" Let's make the answer to this question a resounding testament to the power of living fully, each and every day.
Tom Mathews
Pros and Cons of Simple Interest
Brace yourself: You’ve been brought here under false pretenses.
This post is not so much about a list of pros and cons as it is about one big pro and one big con concerning simple interest accounts. There are many fine-tooth details you could get into when looking for the best ways to use your money. But when you’re just beginning your journey to financial independence, the big YES and NO below are important to keep in mind. In a nutshell, interest will either cost you money or earn you money. Here’s how…
The Pro of Simple Interest: Paying Back Money
Credit cards, mortgages, car loans, student debt – odds are that you’re familiar with at least one of these loans at this point. When you take out a loan, look for one that lets you pay back your principal amount with simple interest. This means that the overall amount you’ll owe will be interest calculated against the principal, or initial amount, that was loaned to you. And the principle decreases as you pay back the loan. So the sooner you pay off your loan, you’re actually lowering the amount of money in interest that you’re required to pay back as part of your loan agreement.
The Con of Simple Interest: Growing Money
When you want to grow your money, an account based on simple interest is not the way to go. Setting your money aside in an account with compound interest shows infinitely better results for growing your money.
For example, if you wanted to grow $10,000 for 10 years in an account at 3% simple interest, the first few years would look like this:
- Year 1: $10,000 + 300 = $10,300
- Year 2: $10,300 + 300 = $10,600
- Year 3: $10,600 + 300 = $10,900
In a simple interest account, the 3% interest you’ll earn is a fixed sum taken from the principal amount added to the account. And this is the amount that is added annually. After a full 10 years, the amount in the account would be $13,000. Not very impressive.
But what if you put your money in an account that was less “simple”?
If you take the same $10,000 and grow it in an account for 10 years at a 3% rate of interest that compounds, you can see the difference beginning to show in the first few years:
- Year 1: $10,000 + 300 = $10,300
- Year 2: $10,300 + 309 = $10,609
- Year 3: $10,609 + 318 = $10,927
At the end of 10 years, this type of account will have earned more than the simple interest account, without you having to do any extra work! And that’s not even considering adding regular contributions to the account over the years! Just imagine the possibilities if you can get a higher interest rate and combine that with a solid financial plan for your future.
One final thought: Simple isn’t always the way to go, and that can be a good thing.
Wise Financial Moves For Retirees
Retiring can be the most exciting time in a person’s life.
You get to relax and do whatever you want, whenever you want, with whomever you want. But it’s important not to forget about your finances AFTER retirement; here are wise financial moves that retirees should consider once they decide to quit working for good.
Get your will in order.
The simple truth is that preparing a will can help ensure that your money goes where you want it to go and save your family a financial headache. If you’re retired and haven’t created a will, do it today!
Plan for long-term care expenses.
Why? Because there’s a strong chance you’ll need it—60% of people will need some form of LTC in their lives.¹ And it can be costly, possibly running into the tens of thousands of dollars. If you’re about to retire or have already retired, consult with a licensed and qualified financial professional about your options for this critical line of financial defense.
Pay off your mortgage!
And, if you’ve played your cards correctly, you should be close to paying off your mortgage by the time you retire. Eliminating your home payments may free up a considerable amount of cash for you to spend on your other bills and your retirement lifestyle.
Consider downsizing your home to a smaller property or RV.
That is of course, unless you have a huge family you regularly plan on entertaining! But for many, retirement is a perfect opportunity to move into a smaller, easier to manage home.
And if you’re the adventurous type, why not buy an RV? It’s a great way to travel and explore the country now that you’re moving into a new phase of life.
If you’re retiring, it doesn’t mean there aren’t a few key money moves left to be made. Consider these suggestions to be the cherry on top of your years of diligent work and savvy saving!
Two Ways to Prepare for Financial Emergencies
It’s not a matter of if, but when an unexpected financial emergency will occur.
So the best way to deal with one is to prepare for it in advance. Below are two extremely effective and relatively easy steps that can help you prepare so that when something does happen, your financial strategy isn’t thrown into disarray because of unplanned expenses.
Start an emergency fund.
Your first goal will be to save up enough money to cover six months of expenses. Then when a small emergency crops up, you’ll be able to dip into this fund. But beware! You’ll need to discern what counts as an emergency—going out to eat because you don’t feel like making dinner or going shopping because there’s a great sale going on doesn’t count!
Make sure you have the right insurance.
Not every issue can be solved with a simple emergency fund; serious medical issues, disability, or death can all cause financial trouble that may fall well beyond the scope of an emergency fund.
There are three things that you need to consider: health insurance, disability insurance, and life insurance. They can help provide protection for your family if you become unable to work or if hospital bills threaten your cash flow.
If you feel unprepared for a financial emergency, contact a licensed and qualified financial professional. They’ll have insights into how you can create an emergency fund, and help you evaluate your options for financial protection.
Why Generation Z's Financial Habits are Fascinating
Gen Z has grown up in a world where social media rules. They’ve never known it any other way.
The older Gen Zers have just come out of college, but this group’s imprint on society is already clear. You might be surprised by their attitude towards money and wealth! Let’s explore how these digital natives interact with money and why their financial habits might be influencing your business strategy.
Social media is an integral part of their world.
They spend more time on their phones, tablets, and laptops than any other generation. The iPhone was old news by the time younger Gen Zers were born. This generation needs a whole new set of rules for how they shop and find financial advice.
For instance, Gen Zers are 72% more likely to buy from brands they follow on social media.¹ And there’s been an explosion of financial advice–not all of it good–on TikTok—#personalfinance has 3.5 billion views on the platform.² So if you’re interested in not just understanding Gen Zers, but also getting their attention, it pays to keep up with social media trends.
Gen Zers have yet to accrue massive debt.
Gen Zers have thus far avoided the traps of credit card and student loan debt that have burdened every generation before. The numbers aren’t stellar–on average, Gen Zers have over $10,000 in non-mortgage debt–but that’s just a fraction of the debt carried by the typical Millennial or Gen Xer.
Of course, Gen Zers haven’t had as much time to accrue debt. It could well be that in 10 years they have just as many student loans and high credit card balances as older generations. But there is hope! Why?
Gen Zers are avid budgeters.
68% of Gen Zers use some form of budgeting system.³ Only 41% of the general population can say the same.⁴ That’s a massive improvement! If Gen Zers can use their budgets to avoid massive debt, they could find themselves well positioned financially.
In other words, Gen Z is hungry to learn how money really works. They’re already taking steps to avoid the missteps of past generations. The real question is who will teach them what it takes to become wealthy?
How Can Graduates Start Building Wealth?
If you’re a recent graduate, congratulations! You made it.
Your degree is in your hands and the world is now your oyster. If there’s one thing you should know, it’s that life after graduation isn’t all about partying with friends and family until next summer rolls around again. No, it’s time to start building wealth!
That’s because you have a secret weapon at your disposal—time.
Your money has the potential to grow via the power of compound interest. The longer your savings accrue interest, the more potential they have to grow.
Let’s say you’re 22 and fresh out of college. You’re able to save just $160 monthly in an account earning 9% interest. After 45 years, you would have grown over $1 million!
And, as your income rises, you can increase your savings rate and level up your goals.
But how can you save $160 per month?
It’s pretty straightforward—you should at least implement a budget ASAP, and maybe even start up a side gig. These are simple ways to decrease unnecessary spending and earn more money that can go towards wealth building.
If you want to learn more about building wealth reach out to financial professional you trust and schedule an appointment! They may have the knowledge and expertise to help you start on the path towards financial indepedence.
Securing the Financial Future of Your Loved Ones
Life insurance – a topic that often leads to a labyrinth of questions, concerns, and misconceptions.
Yet, this misunderstood financial tool holds the potential to secure the future of your loved ones and guarantee peace of mind. As we shine a spotlight on this crucial subject during Life Insurance Awareness Month, we invite you to join us in breaking down barriers, busting myths, and shedding light on statistics that underline the importance of life insurance. This article delves into the numerous facets of life insurance, from addressing coverage gaps and protection voids to exploring the lasting impact of charitable gestures. We aim to transform your understanding of life insurance, empowering you and your family to secure a future filled with financial stability and certainty.
Income Replacement for Loved Ones:
When you're the primary earner, the financial stability of your loved ones hinges on your income. Life insurance ensures that, in your absence, their financial needs are met. This is paramount for families with young children, but it also holds true for couples, where the loss of one income could spell financial distress. Additionally, adults, be they parents, siblings, or grown-up children, who lean on you financially, would find solace in this safety net. This provision becomes all the more crucial if your family's government or employer-related benefits diminish after your passing.
Covering End-of-Life Expenses:
Beyond the emotional turmoil, the end of life also brings significant financial expenditures—funeral arrangements, burial costs, unpaid medical bills, and estate administration expenses. Life insurance ensures these costs don't burden your grieving loved ones.
Establishing a Legacy:
A life insurance policy can be your legacy. Even if you don't possess substantial assets, naming your heirs as beneficiaries ensures they receive a considerable inheritance, creating a lasting financial footprint.
Addressing Estate Taxes:
Inheritance can come with a significant tax burden. Life insurance benefits can shoulder these estate or "death" taxes, safeguarding your heirs from having to downsize their inheritance. While federal "death" tax regulations are evolving, it's noteworthy that some states are compensating with their adjustments to estate tax protocols.
Charitable Gestures with Lasting Impact:
Elevate your charitable inclinations by designating a charity as your life insurance beneficiary. This act transforms your policy premiums into a generous contribution, amplifying the impact of your generosity.
A Reinforced Savings Strategy:
Some life insurance policies come with a cash value component. If not claimed as a death benefit, this can be accessed as a loan or withdrawal. This not only encourages a disciplined savings habit but also offers the advantage of tax-deferred growth. If this amount becomes part of a death claim, it's tax-exempt, maximizing benefits for your beneficiaries.
Life insurance is more than just a policy; it promises financial security, legacy preservation, and peace of mind. Invest wisely today to ensure your loved ones are cushioned against the unforeseeable tomorrows.
Coverage Gap: According to LIMRA (Life Insurance and Market Research Association), about 60% of all people in the U.S. are covered by life insurance. However, many insured are underinsured, meaning they might not have enough coverage to meet their beneficiaries' needs upon death.
Protection Void: As per LIMRA's research, nearly 50% of U.S. households said they would need more life insurance within the next year, highlighting the need for increased coverage.
Immediate Concerns: A study found that 35% of households would feel the financial impact within one month if the primary wage earner died.
Future Prospects: The younger generation isn't as covered as they should be. A recent LIMRA study found that only about 54% of millennials own life insurance despite many having families.
Overestimation: According to LIMRA and Life Happens, over half of millennials overestimate the cost of a term life insurance policy. This overestimation is a significant barrier to them obtaining coverage.
Employer Coverage Misconception: Many people believe that their employers' life insurance is sufficient. However, employer-provided life insurance often only covers 1-2 years of an employee's salary, which might not be adequate for a family's long-term needs.
Reasons for No Insurance: According to a survey by the Insurance Information Institute, about 44% of respondents said they don't have life insurance because it's too expensive. In comparison, 43% felt they had other financial priorities.
The Earlier, The Cheaper: Premiums for life insurance policies are typically lower the younger and healthier you are when you first buy.
Funeral Costs: The National Funeral Directors Association cites that the median cost of a funeral with a viewing and burial was over $7,848, not including the cemetery, monument, or marker costs. Life insurance can help cover these immediate post-death expenses. https://nfda.org/news/statistics
College Expenses: For parents, a life insurance policy can also ensure that their children's education is funded. In 2022-23, the College Board estimates that the average annual cost (tuition, fees, room and board with allowances for books) for a private four-year college was $57,570 for full-time undergraduate students, the future financial burden can be substantial. https://research.collegeboard.org/media/pdf/trends-in-college-pricing-student-aid-2022.pdf
Life Insurance Awareness
As we commemorate each September as Life Insurance Awareness Month, we're confronted with some alarming statistics that underscore a pervasive gap in both preparedness and comprehension. Yet, it's crucial to remember that awareness isn't just an acknowledgment of these challenges; it's the first, transformative step towards empowerment.
The statistics do not merely present numbers; they unravel stories of families and individuals caught in the crosshairs of unforeseen circumstances, often unprepared. Yet, in the face of these challenges, this month is a beacon of hope. Awareness is the first step on the path to empowerment. With the proper knowledge and proactive measures, we can transform uncertainties into certainties, ensuring our loved ones remain shielded from life's unpredictabilities. Let this month be a reminder and a call to action, prompting each of us to prioritize protection and secure a future filled with promise and peace of mind.
By shining a light on these issues, we're not only highlighting the areas that need attention but also paving the way for informed decisions, proactive planning, and a secure future. Let September catalyze change, prompting individuals to take the reins of their financial destinies and ensure that their loved ones are shielded from unforeseen circumstances.
First Steps Towards Your First Home
If you’ve checked home prices recently, you know that this is a rough time to be a first time house hunter!
2020 witnessed home prices soar by 15% to average more than $320,000–a prohibitive price for many seeking to buy their first house.¹
But even if you aren’t ready to buy a house today, there are steps you can take now that may better position you to become a homeowner in the future!
Build your emergency fund.
An emergency fund is a critical line of financial defense that can help lay the foundation for buying a house. That’s because an emergency fund provides a cash cushion while you prepare to purchase your home and then begin paying off your mortgage. The unexpected expenses of homeownership can be far less detrimental to your long-term goals when you have a dedicated fund specifically designed to cover emergencies!
Increase your credit score.
An excellent credit score is imperative for first time home buyers for two reasons…
First, actions that increase your credit score–debt management and paying your bills on time–can help create a solid financial foundation as you shoulder the responsibility of servicing a mortgage.
Second, lenders typically offer more favorable loan terms to people with high credit scores. That can result in more cash flow over the life of your mortgage. A recent survey discovered that mortgage holders with very good credit scores save more than $40,000 over the lifetime of their loan!²
Take steps to boost your credit score before you start house hunting. Automate your bill payments so they’re always on time, and begin reducing the balances on your credit cards, student loans, and auto loans!
Start saving for your down payment ASAP.
Aim to have a down payment of at least 20% of your future home’s value saved before the home buying process begins.
Why? Because paying more up front and borrowing less to buy your home reduces the interest you’ll owe over the long-term. A substantial down payment might also lower the price of closing costs and negate your need to buy private mortgage insurance. Usually, the higher your down payment, the better!
The time to lay the groundwork for buying your first house is now. Build an emergency fund, increase your credit score, and save enough for a significant down payment. Then, search for a house that meets your needs and won’t break the bank!
Is It Ever OK To Use a Credit Card?
Yes… but with qualifications.
Let’s explore some situations where using your credit card makes sense…and what pitfalls to avoid.
You’re strategically leveraging rewards. It’s perfectly possible to reap the benefits of cash back rewards without going into debt to earn them. How? Try using your credit card just for everyday purchases like gas and groceries. If you don’t overspend, you’re essentially getting paid for using your card.
But that’s the trick. Those rewards can make it tempting to buy things you don’t need. It’s easy to justify excess purchases if you’re earning those extra points! But in the long-term, the rewards won’t outweigh the costs and risks of overusing a credit card. So if you think you can thread the needle of responsibly using a credit card to leverage points without overspending, go for it!
You’re making significant online purchases. The simple fact is that there are serious rewards—and protections—when you use your card for online purchases. This is especially true for travel. Some cards offer specific rewards for booking hotels or plane tickets that you should certainly take advantage of. There are also some protections for online purchases that credit cards offer. Once again, don’t plan a fancy vacation just to take advantage of rewards. But if you need to travel, you might as well get any benefits coming to you!
Wisely using credit cards is a matter of self-control. If you can take advantage of rewards and protections without overspending, good for you! For others, however, it may be wise to avoid cards altogether while they pay down their debt.
Not sure which strategy is best for you? Contact a licensed and qualified financial professional. They can help evaluate your situation and make a recommendation.
Bad Financial Habits and How to Overcome Them
Read on if you ever find yourself struggling to stay afloat financially.
Do you ever feel like no matter how much money you make, it never seems like enough? You’re not alone. A recent survey found that more than half of middle-income families didn’t have three months of expenses saved.¹ Debt and spending can be out of control for many reasons—the economy, our upbringing, or even because we’re hardwired to want more. This article explores three bad habits that may be hurting your financial situation. You might be surprised by what they are!
Treating credit cards like free money. When you’re tempted to buy something and don’t have the cash, it’s easy to just use credit. But instant gratification can have serious consequences. Little by little, you may find yourself racking up more and more debt. Paying your monthly credit card bill can start requiring all of your cash flow… and maybe more. Yikes.
The solution? Limit your credit card usage as much as possible. Make a habit of only using your credit card for certain low-dollar items, like gas. If you can’t buy your impulse purchase in cash, go home!
Trying to buy happiness.
It’s tempting to think that you’re going to be happy if you buy one thing or another. But what happens when the newness wears off? Suddenly, you have a closet full of clothes and shoes that really aren’t making you any happier! The same is true of houses, cars, gadgets, anything you can think of. Buying things to keep up appearances or just because you think they’ll make you fulfilled is a recipe for overspending on things that, ultimately, don’t matter.
The key is to find happiness beyond your material possessions. That’s no small task, and there’s no set road map for it. But it’s absolutely critical to find a source of meaning that isn’t tied to stuff and things. You could be happier—and more financially stable—for it.
Ignoring your financial situation.
Let’s face it—finances can be scary! Overwhelming debt, paying for college, and feeling out of your depth are uncomfortable emotions. And ignoring and denying uncomfortable feelings is often a first line of defense.
But it’s a dangerous game. Ignoring what the numbers tell you can lead you deeper and deeper into financial instability. You could be setting up a much harder path for yourself in the future than if you tackled your financial situation now.
Tackling your financial fears isn’t always easy. It might require serious soul searching. Just know these three things…
Acknowledging the problem is the first step. Once you can admit that your finances need help, you’re ready to start making positive changes.
Seeking help is always wise. Whether it’s a friend, spouse, qualified counselor, or financial professional, enlisting help can give you the courage you need to face your fears.
You can do this! It might not feel like it, but you have what it takes to confront this challenge… and win! Don’t lose hope, and start moving forward.
Managing your money wisely requires more than knowing different techniques and strategies. It takes maturity. The more you invest in making improvements to your life overall, the better emotionally equipped you’ll be to navigate the world of personal finances.
Evaluating the Opportunity Costs of Your Career
Have you ever had a job that didn’t inspire you?
You know, one where you felt as if all your energy was being drained from the moment you walked in until the moment they kicked you out. Maybe it was a bad boss, or just something about the industry or type of work.
This article will help you evaluate whether or not your current career path is worth pursuing by considering the opportunity cost of staying where you are versus leaving to pursue your dreams.
First off, what is opportunity cost? It’s an economic term which refers to the benefit that a person must give up in order to attain something else. Typically, it’s calculated in dollars. For instance, career A might pay you $50,000 while career B may pay only $30,000. The opportunity cost of choosing career B would be $20,000.
But here’s the catch—there are factors beyond pay that you must consider when choosing a career.
What if earning boatloads in your career requires dedicating all your waking hours to that endeavor? Are you sacrificing your joy, freedom, or even mental health just for a paycheck? The opportunity cost of your career and salary might be your joy, your freedom, your family, and your state of mind!
So when considering a job or a career, weigh ALL the costs. Will your career consume your time, distract you from your true passions, and impair your mental health, all in exchange for a fat paycheck? Or will it enrich your life, use your time wisely, and allow you to make enough money without sacrificing the joys of family and friends?